
You no longer need a nurse visit, blood draw, or weeks of waiting to get meaningful term life coverage. Many insurers now approve healthy applicants for $500,000, $1 million, or more using electronic records instead of a physical exam. Some decisions come back within minutes. But “no exam” covers three very different types of policies, with very different limits and prices. This guide explains how no-exam term life works, compares the options, shows 2026 sample rates, and walks through how to qualify.
Quick answer: Term life insurance with no medical exam uses health questions and database checks (MIB, prescription history, driving records) instead of a physical exam. Healthy applicants under about 60 can often get $1 million or more through accelerated underwriting. A healthy 30-year-old pays about 33–40 a month for a $500,000, 20-year policy.
How does term life insurance with no medical exam work?
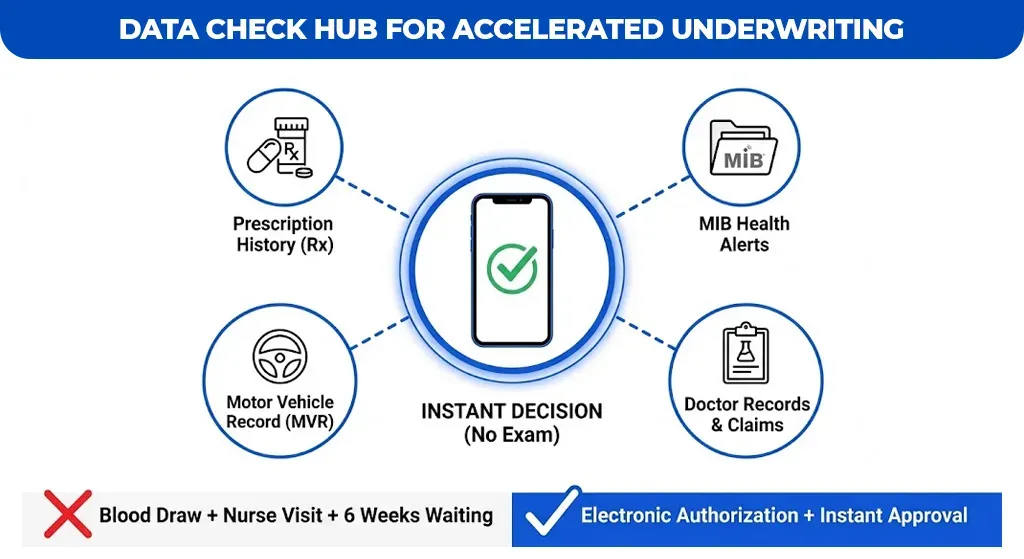
No-exam term life insurance replaces the paramedical examination (blood, urine, blood pressure, height and weight) with a detailed application and electronic database checks. If the data supports your answers, the insurer can approve you without a nurse visit, sometimes the same day. If not, it may ask for an exam or more records.
How accelerated underwriting uses your data
With accelerated underwriting (AU), the insurer’s system checks your application against several databases, with your signed authorization:
| Data source | What it shows |
| Medical Information Bureau (MIB) | Coded alerts from past life or health insurance applications, such as medical conditions, hazardous hobbies, or adverse driving records |
| Prescription history (Rx check) | Medications filled in recent years, which point to diagnosed conditions |
| Motor vehicle report (MVR) | Driving violations, DUIs, and license suspensions |
| Medical claims and records | Lab results, diagnoses, and doctor visits, depending on the carrier |
| Credit-based or public records data | Some carriers use credit-based insurance scores, bankruptcies, or criminal records |
MIB says member insurers must give you an MIB Pre-Notice and get your signed authorization before checking its database, and codes stay on file for seven years. MIB generally doesn’t report codes for healthy applicants approved at standard or preferred rates.
Note: Answer every health question honestly. The data checks are designed to catch mismatches, and misstatements can lead to a decline or a contested claim later.
Level term protection
Most no-exam term policies are level term life insurance: your premium and death benefit stay the same for 10, 15, 20, or 30 years. Many also include a conversion option to switch to permanent coverage without a new medical exam, and an accelerated death benefit rider that lets you use part of the benefit early if you’re diagnosed with a terminal illness. See Assurance Gurus’ level term life insurance and convertible term life insurance pages.
Types of no-exam term life: accelerated vs. simplified vs. guaranteed issue
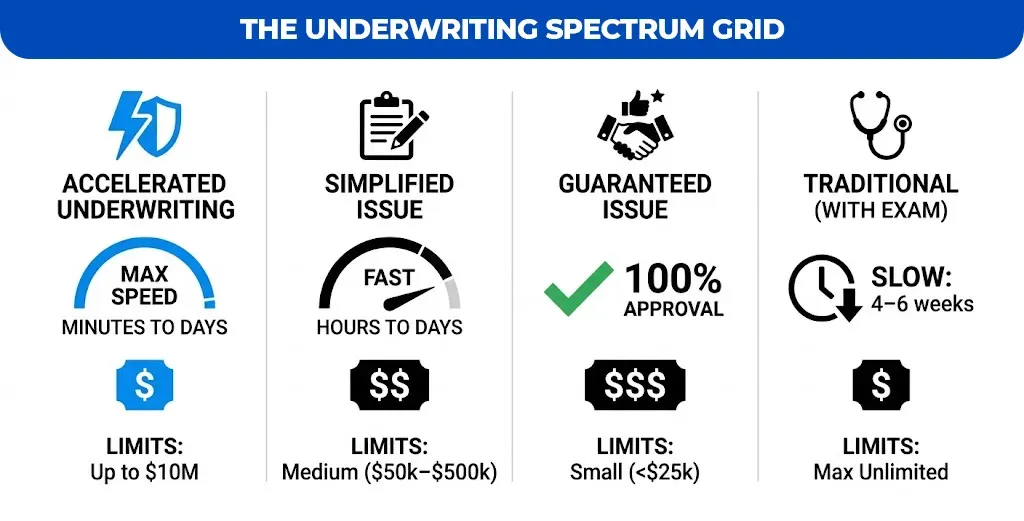
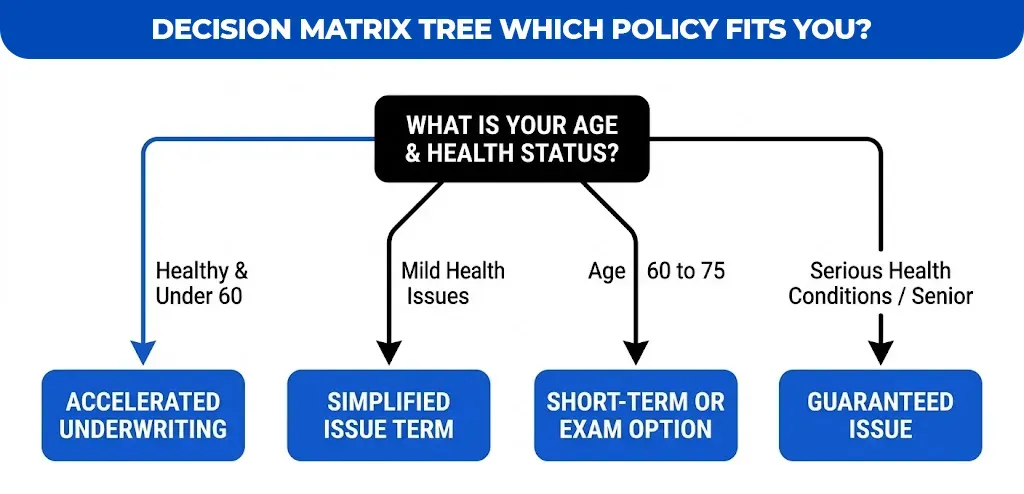
There are three kinds of no-exam life insurance. Accelerated underwriting gives healthy applicants high limits at fully underwritten prices. Simplified issue is easier to qualify for but has lower limits and higher prices. Guaranteed issue accepts almost anyone but offers small amounts, usually as whole life with a waiting period.
Accelerated underwriting
Accelerated underwriting is the best option if you’re healthy. You answer a full health questionnaire, the insurer checks databases, and many approved applicants pay the same price as people who took an exam. No-exam limits are high: MoneyGeek’s 2026 review lists maximums of $1.5 million at Nationwide, $3 million at Pacific Life and Ethos, $4 million at Banner Life, and $10 million at Penn Mutual. Eligibility usually ends between ages 55 and 65 depending on the carrier, and there’s no waiting period once the policy is issued.
Simplified issue term life
Simplified issue term asks fewer health questions and relies less on detailed records, so it’s easier to pass with mild health conditions. The trade-offs are lower coverage limits and higher premiums. State Farm’s Instant Answer Term, for example, offers $50,000 of coverage with health questions and no exam. Decisions are often fast, sometimes instant.
Guaranteed issue life insurance
Guaranteed issue policies ask no health questions and require no exam. They’re almost always small whole life policies for older adults, and most have a graded death benefit: if you die of natural causes in the first two years, beneficiaries typically get premiums back plus interest instead of the full benefit. AAA, for example, sells guaranteed issue whole life to ages 45–85. See Assurance Gurus’ guaranteed issue life insurance.
Underwriting spectrum comparison
| Feature | Accelerated underwriting | Simplified issue | Guaranteed issue | Traditional (with exam) |
| Health questions | Full questionnaire | Short questionnaire | None | Full questionnaire |
| Medical exam | No (if approved) | No | No | Yes |
| Typical max coverage | 1M–10M depending on carrier | Lower; often tens to hundreds of thousands | Small; usually $25,000 or less | Highest |
| Approval speed | Minutes to days | Minutes to days | Usually immediate | Several weeks |
| Relative premium | Same as or close to fully underwritten | Higher | Highest per $1,000 | Lowest for healthy applicants |
| Waiting period | None | Usually none | Usually 2-year graded benefit | None |
| Best for | Healthy applicants under about 60 | Mild health issues or small needs | Serious health issues, older adults | Large policies, complex health, best rates |
Note: Limits change often and vary by age. If you don’t qualify for accelerated underwriting, the insurer may offer to continue with a traditional exam instead of declining you.
See Assurance Gurus’ life insurance without a medical exam guide.
Monthly cost benchmarks: $500k and $1 million no-exam term
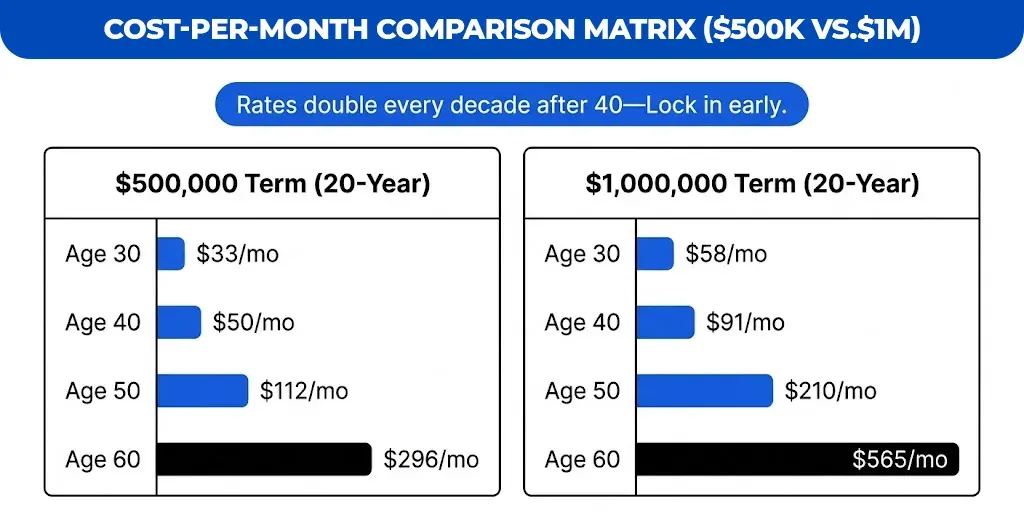
No-exam term life is affordable for younger, healthy applicants and gets much more expensive after 50. MoneyGeek’s 2026 averages show a $500,000, 20-year policy at about 33–40 a month at age 30, 50–63 at 40, 112–149 at 50, and 296–408 at 60.
What drives the price
• Age: The biggest factor. Rates roughly double or more with each decade after 40.
• Gender: Women pay less because they live longer on average.
• Coverage amount: $1 million costs less per $1,000 than $250,000, but more in total.
• Term length: A 30-year term costs more than a 20-year term because it covers older ages.
• Tobacco use: Smokers often pay several times more than non-smokers.
• Health class: The rates below assume average health; excellent health can lower them.
2026 sample monthly rates: $500,000 no-exam term
| Age | 20-year term, women | 20-year term, men | 30-year term, women | 30-year term, men |
| 30 | $33 | $40 | $59 | $72 |
| 40 | $50 | $63 | $93 | $117 |
| 50 | $112 | $149 | $218 | $302 |
| 60 | $296 | $408 | Not shown | Not shown |
2026 sample monthly rates: $1 million no-exam term
| Age | 20-year term, women | 20-year term, men | 30-year term, women | 30-year term, men |
| 30 | $58 | $71 | $110 | $137 |
| 40 | $91 | $116 | $176 | $225 |
| 50 | $210 | $282 | $413 | $580 |
| 60 | $565 | $806 | Not shown | Not shown |
For a $250,000 policy, the 20-year average is about 21–24 a month at age 30 and 30–37 at 40.
Note: Rates are MoneyGeek’s averages for non-smokers in average health across no-exam insurers (updated October 2, 2026). The source doesn’t publish 10-year rates or 30-year rates at age 60, since many insurers won’t issue a 30-year term that late. Your actual price depends on your health and the carrier.
Senior term life insurance with no medical exam
Senior term life insurance with no medical exam is available, but options shrink with age. Accelerated underwriting usually ends between 55 and 65, depending on the carrier. Some simplified issue products go older; MoneyGeek lists Transamerica at ages 18–80, and AAA’s ExpressTerm has been sold to age 75. For older applicants, ways to save include:
• Choosing a shorter term (10 or 15 years) that matches your actual needs
• Buying a smaller amount to cover a mortgage or final expenses
• Taking a medical exam if you’re healthy, since it can unlock better rates
• Considering final expense whole life for smaller, permanent needs
See Assurance Gurus’ term life insurance for seniors and life insurance for seniors.
Carrier comparison: AAA, State Farm, and independent marketplaces
Big-name brands like AAA and State Farm offer no-exam term options, but their no-exam limits are modest compared with the accelerated underwriting programs of carriers like Banner Life, Pacific Life, and Penn Mutual. An independent agency can compare all of these at once.
AAA term life insurance with no medical exam
AAA Life’s ExpressTerm has been sold as a no-exam term policy for ages 20–75, with coverage from $25,000 to $500,000 and terms of 10, 15, 20, or 30 years, according to Policygenius’s review. NerdWallet’s 2026 review notes that AAA’s traditional term goes up to $3.5 million with an exam, that you don’t need to be a member to buy, and that members save 10% on term premiums. Policygenius rated AAA’s no-exam rates as relatively high.
State Farm term life insurance with no medical exam
State Farm’s Instant Answer Term offers $50,000 of coverage with health questions and no medical exam. Coverage lasts until age 50 or for 10 years after issue, whichever is later. For larger amounts, State Farm’s Select Term starts at $100,000. NerdWallet found you generally need to work with a State Farm agent to complete a term application.
Carrier feature comparison
| Carrier | Ages (no exam) | Max no-exam coverage | Notes |
| AAA (ExpressTerm) | 20–75 | $500,000 | Member discount on some policies |
| State Farm (Instant Answer Term) | Not published | $50,000 | Agent required for most term sales |
| Nationwide | 21–55 | $1.5 million | Accelerated underwriting |
| Banner Life | 20–60 | $4 million | Terms up to 40 years |
| Transamerica | 18–80 | $2 million | Terms up to 30 years |
| Pacific Life | 18–60 | $3 million | Smokers up to $2 million |
| Penn Mutual | 20–65 | $10 million | Accelerated underwriting |
| Ethos | 20–65 | $3 million | Online application |
Why independent agencies often find better prices
A captive agent can sell only one company’s products. An independent agency compares several carriers, which matters because each insurer’s accelerated underwriting rules differ. One may approve you for $1 million without an exam while another asks for bloodwork, and prices for the same person can vary widely.
Term life insurance with no medical exam in New York
Term life insurance with no medical exam in New York is available, but options can differ. Many national insurers sell in New York through a separate New York company with its own products, so limits and prices may not match other states. New York also regulates how insurers use data: the Department of Financial Services’ Circular Letter No. 7 (July 2024) says insurers shouldn’t use external consumer data or AI in underwriting unless they can show it doesn’t unfairly discriminate. It also says applicants should be told the specific reasons, and the data sources, behind an adverse decision.
Note: The AAA ExpressTerm details come from a review last updated in 2023. Confirm current ages and limits when you apply.
How to avoid a medical exam and get approved fast
To give yourself the best chance at no-exam approval: choose the right amount and term, answer health questions accurately, apply with carriers whose accelerated underwriting fits your profile, and authorize the database checks. Healthy applicants under about 60 have the best odds.
Step 1: Calculate your coverage and choose a term
Add up income replacement, mortgage and debts, children’s education, and final expenses, then subtract savings and existing coverage. Match the term to your longest obligation, such as 20 years until the kids are grown or 30 years for a new mortgage. Try the Assurance Gurus life insurance calculator.
Note: Staying within a carrier’s no-exam limit for your age matters. Asking for $2 million when the limit is $1 million may trigger an exam.
Step 2: Prepare your health details
Have the names and dates of medications, diagnoses, surgeries, and doctors ready. Accurate answers that match your prescription and MIB records are the main reason accelerated applications get approved without delays.
Step 3: Run an online quote
Get a term life insurance no medical exam online quote through an independent agency so you can compare several carriers’ prices and no-exam limits at once.
Step 4: Authorize the database checks
Sign the authorizations for MIB, prescription history, and motor vehicle reports. Some carriers also ask to see medical records or do a short phone interview.
Step 5: Get your decision and policy
If you qualify, you may get a decision within minutes or a few days, and many carriers deliver the policy electronically. Accelerated underwriting policies have no waiting period once they’re in force. If the insurer needs more information, it may ask for an exam; that isn’t a decline.
Conclusion:
Term life insurance with no medical exam lets many healthy people get $500,000 to $1 million or more without a nurse visit, often at the same price as a fully underwritten policy. The key is to understand which type you’re buying and to compare carriers, because no-exam limits and prices vary widely.
| Your situation | Best no-exam option |
| Healthy, under about 60, needs 250k–1M+ | Accelerated underwriting term |
| Mild health conditions, smaller need | Simplified issue term |
| Serious health issues, need final expense coverage | Guaranteed issue whole life |
| Age 60–75 | Simplified issue term with a shorter term, or take an exam for better rates |
| Living in New York | Compare New York-licensed carriers’ products |
| Want the lowest possible rate and are very healthy | Consider a traditional exam |
Compare no-exam term quotes at Assurance Gurus
Assurance Gurus helps families across the United States compare term life options, including no-exam policies, so they can lock in level coverage without unnecessary delays. Assurance Gurus life specialists can help you find carriers whose no-exam limits and health guidelines fit you.
Get instant term life quotes on Assurance Gurus. See also term life insurance quotes.