
Veterans have access to life insurance programs most civilians don’t: guaranteed coverage for service-connected disabilities, and the right to keep military coverage after leaving the service without a medical exam. Those programs have limits, though. VALife caps out at $40,000, and VGLI premiums rise sharply with age. Many veterans also need private coverage to fully protect their families. This guide explains each VA program, shows 2026 rates, compares VGLI with private term life, and walks through filing a claim.
Quick answer: Veterans with a VA service-connected disability rating (even 0%) can get up to $40,000 of guaranteed-acceptance whole life coverage through VALife. At age 40, $40,000 costs $88 a month. Separating service members can convert SGLI to VGLI term coverage (up to $500,000) without a health review if they apply within 240 days. Healthy veterans can often get cheaper level rates from private insurers.
Overview of veterans life insurance options
Veterans life insurance comes in two forms: government programs run by the Department of Veterans Affairs (VA) and private policies from commercial insurers. The VA offers SGLI for current service members, VGLI for those who’ve separated, and VALife for veterans with service-connected disabilities. Private insurers offer term and permanent policies with higher limits and, for healthy applicants, often lower rates.
Do veterans get life insurance for free?
No. VA life insurance programs require premiums. A few points cause confusion:
• SGLI isn’t free; active-duty members pay $26 a month for $500,000 (including traumatic injury coverage), deducted from base pay.
• VALife has no premium waiver, even for veterans rated 100% disabled.
• S-DVI (Service-Disabled Veterans’ Life Insurance), now closed to new applicants, still waives basic premiums for some totally disabled veterans with existing policies.
• Burial and survivor benefits (such as VA burial allowances or Dependency and Indemnity Compensation) are separate VA benefits, not life insurance.
Who has the best life insurance for veterans?
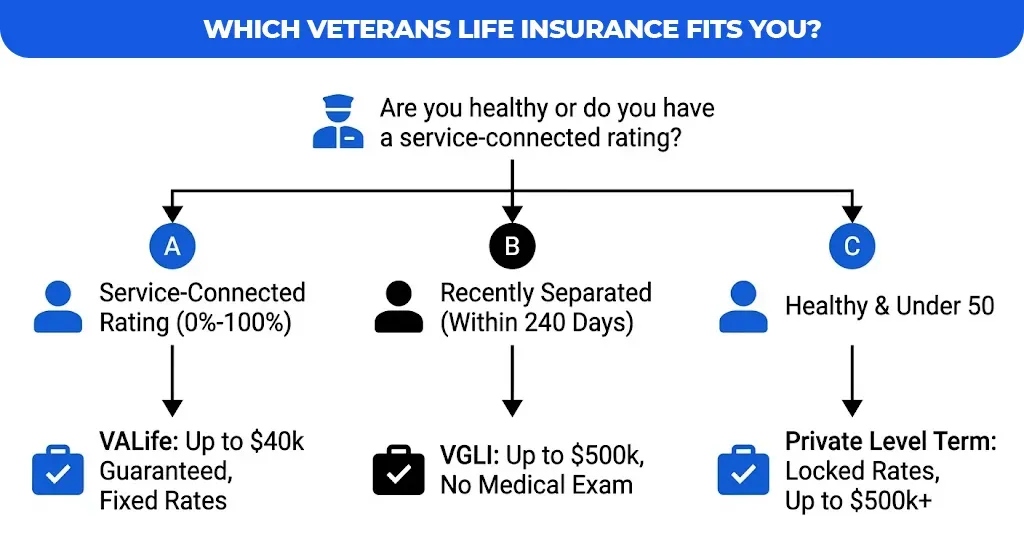
It depends on your health and needs:
| Your situation | Often the best fit |
| Service-connected disability, health issues, need a small permanent policy | VALife (guaranteed acceptance) |
| Just separating, want to keep coverage without a health review | VGLI (apply within 240 days) |
| Healthy veteran under 50 needing large coverage | Private level term life |
| Want lifelong coverage above $40,000 | Private whole or universal life |
Many veterans combine programs: for example, VALife for guaranteed final expense coverage plus a private term policy for income replacement. See Assurance Gurus’ life insurance overview.
Government-sponsored VA life insurance programs
The VA’s current life insurance programs are SGLI for active service members, VGLI for veterans converting SGLI after separation, and VALife for veterans with service-connected disabilities. S-DVI, the older disability program, closed to new applicants after December 31, 2022.
Veterans Affairs Life Insurance (VALife)
VALife is guaranteed-acceptance whole life insurance for veterans with a VA service-connected disability rating from 0% to 100%:
• Eligibility: Age 80 or younger with a service-connected rating; there’s no deadline to apply after your rating. Veterans 81 or older qualify only if they applied for disability compensation before 81, received the rating after turning 81, and apply within 2 years of being notified.
• Coverage: Up to $40,000, in $10,000 increments.
• Underwriting: No health questions or medical exam; approval is automatic if you’re eligible.
• Waiting period: Full coverage starts 2 years after you apply. If you die during that time, beneficiaries receive premiums paid plus interest (4.23% for deaths in 2026).
• Premiums: Set by your age at application and never increase. Cash value begins building after 2 years. There are no loans or premium waivers.
How much is $40,000 VA life insurance?
VALife premiums depend on your age when you apply. For $40,000 of coverage, a veteran pays about $61.60 a month at 30, $88 at 40, $130 at 50, $200 at 60, $312 at 70, and $510 at 80. The full chart is in the next section.
Veterans’ Group Life Insurance (VGLI)
VGLI lets you keep group term coverage after leaving the military:
• Coverage: $10,000 to $500,000, up to the amount of SGLI you had at separation.
• Deadline: Apply within 1 year and 120 days of separation. Apply within 240 days and no health review is required.
• Increases: You can add $25,000 one year after getting VGLI and every 5 years after that, up to $500,000, until age 60.
• Premiums: Based on 5-year age bands, rising as you get older; renewable for life.
Servicemembers’ Group Life Insurance (SGLI)
SGLI is low-cost term coverage for service members, up to $500,000 in $50,000 increments. The full $500,000 costs 26amonth(25 basic plus $1 for traumatic injury coverage), deducted from base pay. SGLI ends after separation unless you convert it to VGLI or a commercial policy.
S-DVI: the program VALife replaced
S-DVI closed to new applications after December 31, 2022, and Supplemental S-DVI closed at the same time. Existing policyholders can keep their coverage. If you apply for VALife on or after January 1, 2026, your S-DVI ends the day VALife is approved, so you’d have no full coverage during VALife’s 2-year waiting period. Some totally disabled veterans have S-DVI premiums waived, and VALife doesn’t offer that waiver.
Note: Before switching from S-DVI to VALife, compare your coverage, premiums, and any premium waiver carefully.
VALife vs. VGLI vs. SGLI
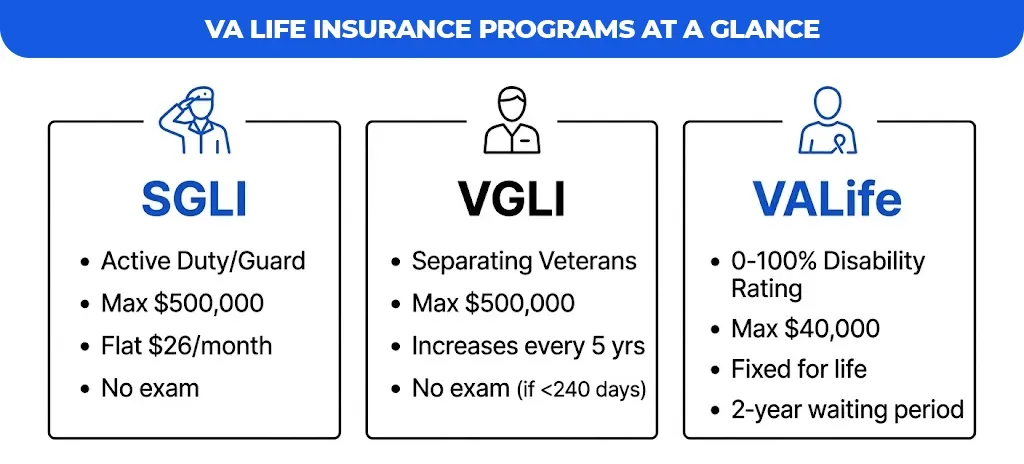
| Feature | VALife | VGLI | SGLI |
| Who it’s for | Veterans with a service-connected disability rating (0–100%) | Separating service members and veterans | Active-duty and eligible Reserve/Guard members |
| Policy type | Whole life | Renewable term | Group term |
| Medical exam needed? | No | No if you apply within 240 days | No |
| Maximum coverage | $40,000 | $500,000 | $500,000 |
| Rate structure | Fixed for life, based on age at application | Rises with 5-year age bands | Flat ($26/month for $500,000) |
| Waiting period | 2 years for full benefit | None | None |
Disabled veterans life insurance
VALife is the main life insurance program for disabled veterans. Any service-connected disability rating, from 0% to 100%, qualifies, and acceptance is guaranteed regardless of health. That makes it valuable for veterans whose conditions make private coverage expensive or hard to get.
Qualifying with a service-connected disability
You need a VA service-connected disability rating. It can be for any condition the VA has connected to your service, such as PTSD, traumatic brain injury, musculoskeletal injuries, hearing loss, or chronic illnesses. Even a 0% rating qualifies. Spouses of disabled veterans aren’t eligible for VALife.
VALife monthly premiums by age and coverage
| Age at application | $10,000 | $20,000 | $30,000 | $40,000 |
| 18 | $10.90 | $21.80 | $32.70 | $43.60 |
| 25 | $13.20 | $26.40 | $39.60 | $52.80 |
| 30 | $15.40 | $30.80 | $46.20 | $61.60 |
| 35 | $18.30 | $36.60 | $54.90 | $73.20 |
| 40 | $22.00 | $44.00 | $66.00 | $88.00 |
| 45 | $26.60 | $53.20 | $79.80 | $106.40 |
| 50 | $32.50 | $65.00 | $97.50 | $130.00 |
| 55 | $40.10 | $80.20 | $120.30 | $160.40 |
| 60 | $50.00 | $100.00 | $150.00 | $200.00 |
| 65 | $62.00 | $124.00 | $186.00 | $248.00 |
| 70 | $78.00 | $156.00 | $234.00 | $312.00 |
| 75 | $99.50 | $199.00 | $298.50 | $398.00 |
| 80 | $127.50 | $255.00 | $382.50 | $510.00 |
Per-10,000ratesfromChoiceMutual’sVALifechart,whichmatchVA.gov’spublishedexamples(15.40 at 30, $22 at 40, $50 at 60, $127.50 at 80); higher amounts are multiples. The VA counts you as one year older if more than 6 months have passed since your last birthday.
Note: VALife’s guaranteed acceptance comes with a 2-year waiting period. If you’re healthy enough to qualify for private coverage with full benefits from day one, compare prices first, especially at older ages.
Death benefit tax protections
Life insurance death benefits are generally excluded from beneficiaries’ federal income under IRC §101(a). In addition, under 38 U.S.C. §5301, benefits paid under laws administered by the VA are generally exempt from taxation and from creditors’ claims, though not from claims by the federal government.
Private life insurance for military veterans
Healthy veterans often get more coverage for less money from private insurers than from VGLI, because private level term locks in one premium for 10 to 30 years while VGLI premiums rise every five years. VGLI’s advantage is that it requires no health review if you apply within 240 days of separation.
Why healthy veterans often choose private term over VGLI
• Locked-in rates: A 20-year level term premium doesn’t change, while VGLI rises with each 5-year age band.
• Lower cost when healthy: Private insurers price by health class; VGLI charges everyone in an age band the same.
• Larger or longer coverage: Private carriers offer term lengths and amounts that fit a mortgage or children’s ages.
VGLI makes more sense if you have health conditions that would raise private rates or lead to a decline, or if you need coverage right away while you shop.
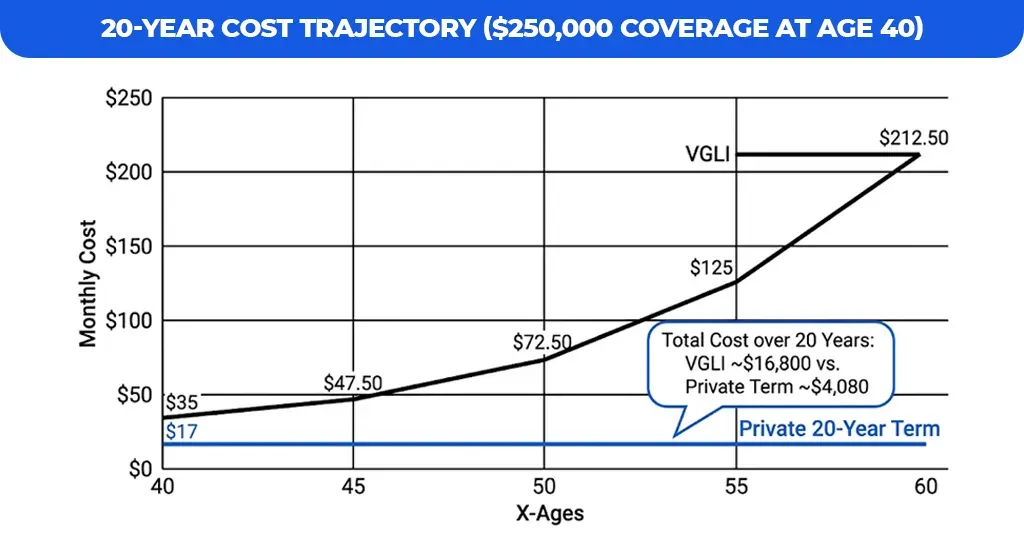
VGLI vs. private level term: $250,000 of coverage
| Age | VGLI monthly (age band) | Private 10-year term (preferred) | Private 20-year term (preferred) |
| 30 | $20.00 (30–34) | 9–10 | 11–12 |
| 40 | $35.00 (40–44) | 11–12 | 15–17 |
| 50 | $72.50 (50–54) | 20–23 | 31–38 |
| 60 | $212.50 (60–64) | 39–58 | 73–104 |
| 65 | $345.00 (65–69) | 67–99 | 137–192 |
VGLI rates from VA.gov (as of July 1, 2025), calculated at $250,000. Private rates are Choice Mutual preferred non-tobacco samples (valid March 9, 2026), women to men; you must qualify medically.
Example: A 40-year-old man keeping $250,000 of VGLI for 20 years would pay about $35, $47.50, $72.50, and then $125 a month across four age bands, roughly $16,800 in total, if rates stay the same. A preferred 20-year private policy at $17 a month would cost about $4,080 over the same period.
Note: Don’t let VGLI or SGLI lapse until a private policy is approved and in force. Missing the VGLI deadline means losing the no-health-review option.
Comparing private carriers
Veterans can buy from any licensed insurer, including large companies such as New York Life, MassMutual, Mutual of Omaha, and Banner Life. When comparing:
• Check financial strength ratings from AM Best or S&P.
• Ask how the insurer treats your service history, including deployment plans, service-connected conditions, and medications.
• Compare level term lengths that match your mortgage or children’s ages.
• Look for conversion options to permanent coverage without a new exam.
See Assurance Gurus’ term life insurance, level term life insurance, and whole life insurance pages.
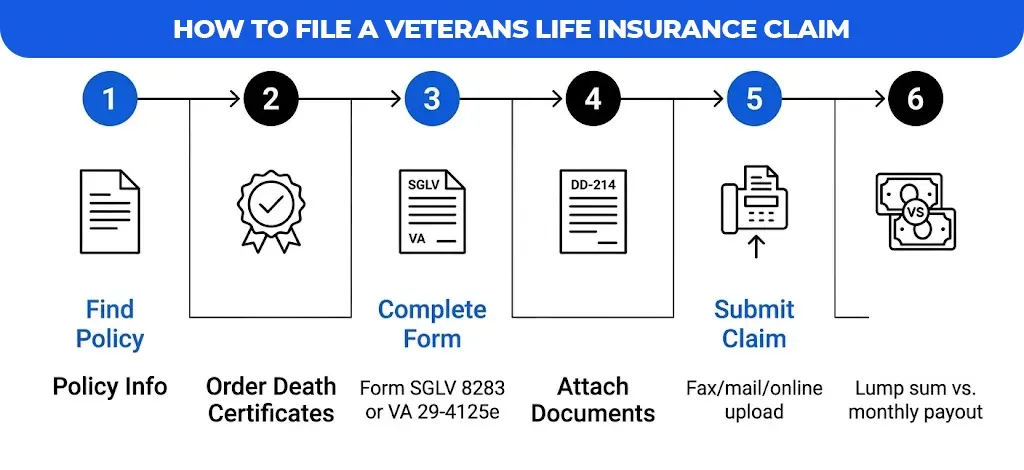
How to file a veterans life insurance claim
The claim form depends on the program. SGLI and VGLI claims go to the Office of Servicemembers’ Group Life Insurance (OSGLI) on Form SGLV 8283. Claims for VA-administered policies are filed with VA Form 29-4125e, Claim for One Sum Payment. Private policies use the insurer’s own claim form.
Required documentation
• Certified death certificate for the insured
• Claim form for the program (see below)
• Separation documents such as a DD Form 214 when the insured wasn’t on active duty at death (for SGLI)
• Beneficiary identification and, for estates or minor beneficiaries, legal documents such as letters of administration or guardianship
Which form to use
| Program | Claim form | Where it goes |
| SGLI (insured on active duty) | SGLV 8283, Claim for Death Benefits | Through the branch of service Casualty Assistance Office to OSGLI |
| SGLI (insured not on active duty) | Death certificate plus DD Form 214, NGB-22, or other separation documents | OSGLI |
| FSGLI (family coverage) | SGLV 8283A | Through the branch Casualty Assistance Office to OSGLI |
| VGLI | SGLV 8283, Claim for Death Benefits | OSGLI by fax (1-877-832-4943) or mail (PO Box 70173, Philadelphia, PA 19176-9912) |
| VA-administered life insurance | VA Form 29-4125e (online); paper VA Form 29-4125 for minor or incompetent beneficiaries | Online, by secure upload, or by mail to the VA Insurance Center, PO Box 5209, Janesville, WI 53547-5209 |
| Private policies | The insurer’s claim form | The insurer, often online |
Per the VA’s “File a death claim” page. Forms and addresses can change; confirm on VA.gov before filing.
Steps to file
1. Find the policy information: program name, policy or service details, and beneficiary designations.
2. Order several certified death certificates from the funeral home or vital records office.
3. Complete the correct claim form and attach required documents.
4. Submit online, by fax, or by mail as instructed.
5. Choose a payout option if offered; VA-administered programs may allow monthly payments instead of a lump sum (call 1-800-669-8477).
6. Keep copies of everything you send.
Disputes and appeals
If a claim is delayed or denied, ask for a written explanation, provide any missing documents, and request a review. Veterans service officers at accredited organizations can help families with VA claims at no cost. For private policies, you can also contact your state insurance department.
Conclusion:
VA programs give veterans valuable options: guaranteed coverage through VALife, and the right to keep coverage through VGLI without a health review. But VALife caps at $40,000, and VGLI gets expensive with age. For many families, the best plan pairs VA coverage with a private policy that locks in rates.
| Your situation | Best starting point |
| Service-connected rating, any health, need final expense coverage | VALife (up to $40,000) |
| Separating now | Apply for VGLI within 240 days, then compare private options |
| Healthy veteran needing $250,000+ | Private level term |
| Have S-DVI with a premium waiver | Compare carefully before switching to VALife |
| Need lifelong coverage above $40,000 | Private whole or universal life |
Compare veterans life insurance at Assurance Gurus
Assurance Gurus helps veterans and military families across the United States compare private term and permanent policies alongside their VA benefits, so you can fill coverage gaps and avoid VGLI’s age-band increases if you qualify. Assurance Gurus veteran specialists can review your current coverage and compare quotes from multiple carriers.
Get custom veteran life insurance quotes on Assurance Gurus or call 888-363-1938.