Whole Life Insurance Quotes

Whole Life Insurance Quotes: Compare Rates & Plans in 2026 

If you are looking for whole life insurance quotes, the price you receive depends on factors such as your age, health, tobacco use, coverage amount, policy design, and the insurance company you choose. Unlike term life insurance, whole life insurance is permanent coverage designed to last for your lifetime as long as the policy remains in force.

A whole life policy generally combines a death benefit with a cash value component. The cash value can grow over time according to the policy’s terms, and some policies may allow you to access it through withdrawals or loans. The exact guarantees, costs, and available features vary by insurer and policy.

When comparing whole life insurance quotes online, don’t look only at the monthly premium. You should also review the guaranteed cash value, death benefit, policy fees, payment schedule, dividends if applicable, riders, and the insurer’s financial strength.

Quick Answer: What Are Whole Life Insurance Quotes?

Whole life insurance quotes are estimates of the premium you may pay for a permanent life insurance policy. A quote is generally based on information such as your age, health, tobacco use, desired death benefit, and policy structure.

Whole life insurance typically provides:

  • Lifetime coverage while the policy remains in force
  • A death benefit for named beneficiaries
  • A cash value component
  • Premiums that are generally structured to remain level under the policy terms
  • Potential access to cash value through policy loans or withdrawals
  • Optional riders or additional benefits, depending on the insurer

The National Association of Insurance Commissioners (NAIC) explains that whole life is a type of cash-value insurance and that whole life policies are designed to build cash value over time.

Important: An online quote is not necessarily the final premium. The insurer may need additional information and underwriting before issuing a policy.

Key Takeaways

  • Compare whole life insurance quotes from multiple insurers rather than relying on one estimate.
  • Whole life insurance is permanent coverage, unlike term insurance, which covers a specified period.
  • Whole life policies can include both a death benefit and cash value.
  • The lowest quoted premium does not necessarily represent the best policy.
  • Review guaranteed values separately from non-guaranteed illustrations.
  • Your age, health, tobacco use, coverage amount, and policy design can affect pricing.
  • Check the insurer’s financial strength and policy terms before purchasing.
  • Never assume that an “instant” or “online” quote is the same as a final approved rate.

What Is Whole Life Insurance?

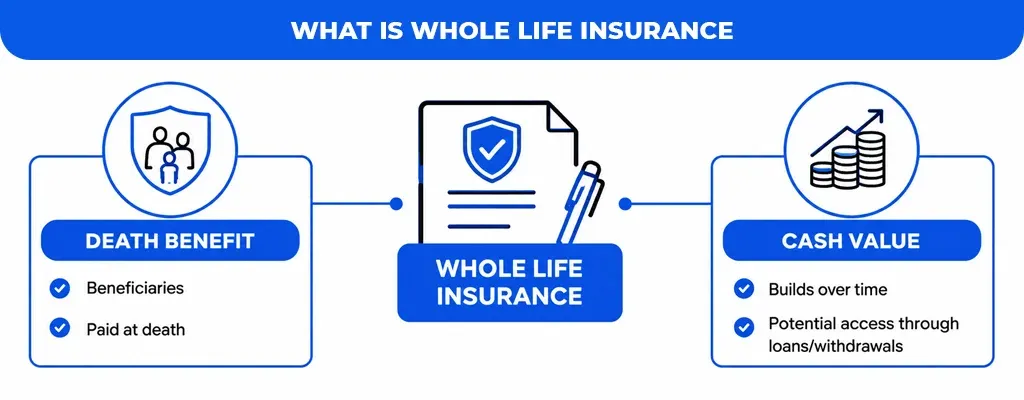
Whole life insurance is a type of permanent life insurance that is designed to provide coverage throughout the insured person’s lifetime. The policy generally has two major components:
What Is Whole Life Insurance

Death Benefit

The death benefit is the amount paid to the policy’s beneficiaries after the insured dies, subject to the policy’s terms and any applicable exclusions or conditions.

The IRS states that life insurance proceeds paid to a beneficiary because of the insured person’s death are generally not included in gross income, although exceptions can apply and interest received on proceeds may be taxable.

Cash Value

A whole life policy can also accumulate cash value. The NAIC identifies whole life as a cash-value policy and explains that policyholders may be able to borrow against cash value. However, accessing cash value can affect the policy. Outstanding loans and interest, for example, may reduce the amount ultimately paid to beneficiaries.

This is why you should examine the policy illustration and contract rather than assuming that every whole life policy works exactly the same way.

How Do Whole Life Insurance Quotes Work?

When you request a whole life insurance quote, the insurer or quoting platform typically evaluates information about you and the coverage you want.

Factors can include:

FactorHow It Can Affect a Quote
AgeAge at application can affect the premium
HealthMedical history and health information can influence underwriting
Tobacco useTobacco use can result in higher premiums
Coverage amountA larger death benefit generally requires a higher premium
Policy designPayment structure and policy features affect cost
RidersAdditional benefits can increase premiums
InsurerDifferent insurers use different underwriting and pricing methods
Payment periodLimited-pay policies may have higher premiums during the payment period

For this reason, a whole life insurance policy quote from one insurer should not automatically be compared with another quote based solely on the monthly payment. You need to confirm that the coverage amount, payment period, policy type, and guarantees are comparable.

️ COMPARE QUOTES TODAY

Online estimates are only the starting point for finding the right policy. Compare accurate whole life insurance quotes tailored to your exact age, health profile, and budget.

What Information Do You Need for a Whole Life Insurance Quote?

The information required varies by insurer and product, but you may be asked for details such as:

  • Age
  • State of residence
  • Gender
  • Tobacco or nicotine use
  • General health information
  • Existing medical conditions
  • Desired coverage amount
  • Occupation
  • Lifestyle information
  • Beneficiary information
  • Desired policy features

Some insurers may offer simplified or no-exam application processes for certain products, while other policies can involve more extensive underwriting. For that reason, whole life insurance instant quotes should be viewed as an initial estimate unless the insurer confirms that the price is final.

Can You Get Whole Life Insurance Quotes Online?

Yes. Many insurers and insurance platforms provide online quoting or application tools. Searching for whole life insurance quotes online can make it easier to begin comparing coverage, but convenience should not replace policy research.

When using an online quoting tool, check whether the displayed amount represents:

  • An estimated premium
  • A preliminary quote
  • A rate based on limited information
  • A fully underwritten offer
  • A final policy premium

A website advertising instant whole life insurance quotes may provide an estimate quickly, while the insurer may still need additional information before approving coverage.

What Affects the Cost of Whole Life Insurance?

There is no single price that applies to every applicant. Two people requesting the same death benefit can receive different premiums because their ages, health profiles, tobacco use, policy structures, or underwriting classifications may differ.

Liberty Mutual similarly identifies factors such as age, health conditions, coverage amount, cash-value growth structure, and dividend options as factors that can affect whole life insurance costs.

Age

Age is an important factor in life insurance pricing. Generally, applying at a younger age can result in lower premiums than waiting until later in life, although the actual rate depends on the insurer and applicant.

Health

Your health history can affect underwriting and pricing. Depending on the policy, an insurer may ask health questions or require additional underwriting.

Tobacco Use

Smoking and other tobacco or nicotine use can affect eligibility and premiums.

Coverage Amount

A policy with a $250,000 death benefit will generally have different pricing from one with a $500,000 or $1 million death benefit.

Policy Design

Payment schedules, riders, participating or nonparticipating structures, and other policy features can affect the quote.

Whole Life Insurance Quotes vs. Term Life Insurance Quotes

When comparing term and whole life insurance quotes, remember that the two products are designed for different coverage needs.

FeatureWhole Life InsuranceTerm Life Insurance
Coverage periodLifetime, subject to policy termsSpecific period
Cash valueYesGenerally no
Premium structureTypically level under the policy termsUsually level during the selected term
Death benefitDesigned to provide lifetime coveragePayable if death occurs during the covered term
CostGenerally higherGenerally lower
Primary purposeLong-term/lifetime protectionTemporary financial protection

The NAIC describes term insurance as coverage for a specified period and whole life as a cash-value form of permanent insurance.

Progressive also notes that whole life generally has higher premiums than term life but provides lifetime coverage and a cash-value component. Therefore, comparing a term quote directly against a whole life quote based only on price can be misleading.
How to Compare Whole Life Insurance Quotes

How to Compare Whole Life Insurance Quotes Online

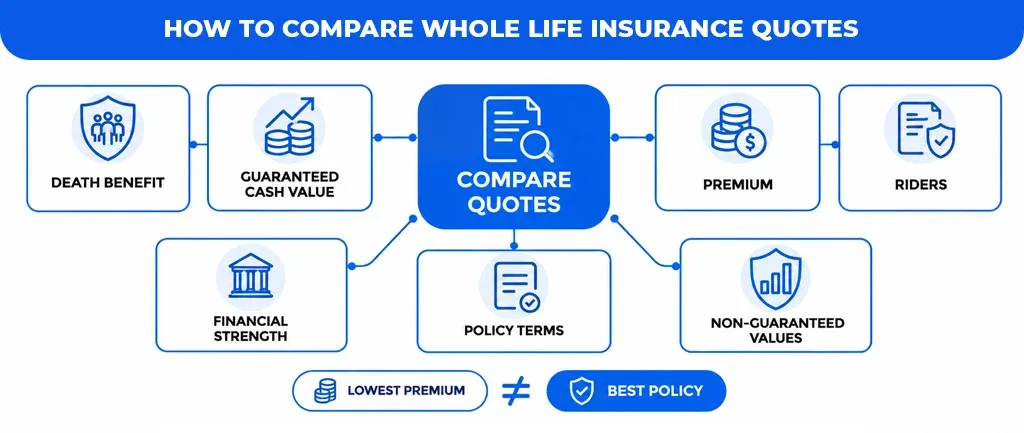
The cheapest quote is not necessarily the most suitable policy. When you compare whole life insurance quotes online, review these factors.

Death Benefit

Start by confirming the amount your beneficiaries would receive under the policy. Make sure you’re comparing the same coverage amount across insurers.

Guaranteed Cash Value

Review the policy’s guaranteed cash-value schedule. The NAIC recommends asking insurers which policy values are guaranteed and which are not.

Non-Guaranteed Values

Some whole life policies may provide dividends or other values that are not guaranteed. Do not treat projected values as guaranteed results.

Premium

Compare the premium and understand whether it is designed to remain level, how long payments are required, and what happens if you stop paying.

Policy Riders

Riders can add additional benefits, but they can also increase premiums. The NAIC notes that adding a life insurance rider can increase the premium.

Financial Strength

Because whole life insurance can remain in force for decades, consider the insurer’s financial strength and reputation when evaluating a policy. Independent financial-strength organizations such as A.M. Best can provide additional information about an insurer’s financial position.

Guaranteed vs. Non-Guaranteed Values

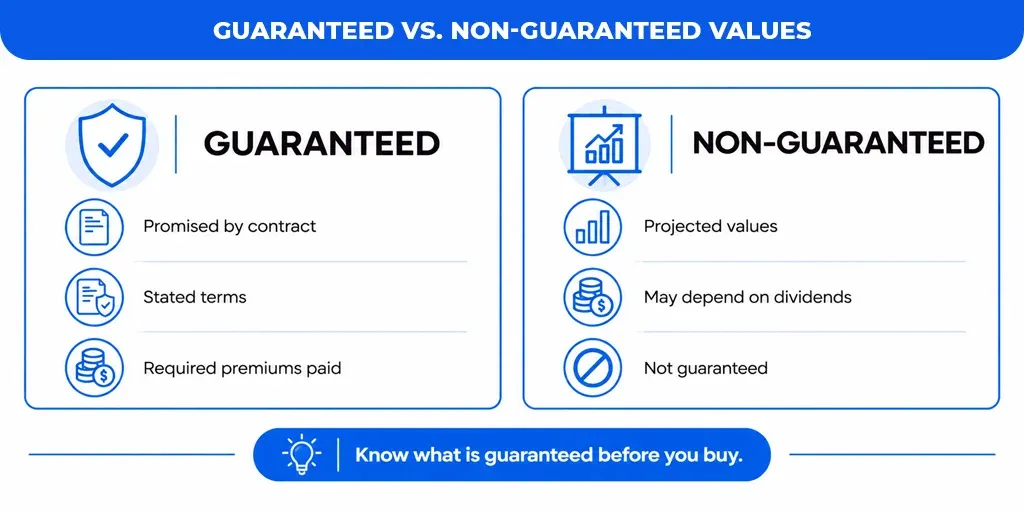
This is one of the most important distinctions when reviewing whole life insurance policy quotes. A policy illustration can contain guaranteed and non-guaranteed values.
Guaranteed vs. Non-Guaranteed Values

Guaranteed Values

These are values the policy contract promises under its stated terms, assuming required premiums are paid and other conditions are met.

Non-Guaranteed Values

These are projections that may depend on factors such as dividends or other assumptions. The NAIC specifically recommends asking what portion of the policy’s premium or values are not guaranteed and requesting an illustration showing future values and benefits.

Whole Life Insurance Quote for Seniors

Older applicants can also explore whole life insurance, but available products, coverage amounts, underwriting requirements, and premiums vary considerably by insurer. Some smaller whole life policies are designed around final expenses. Liberty Mutual, for example, describes small whole life policies as potentially being used for burial and final expenses.

When comparing AARP whole life insurance quotes or quotes from other providers, don’t focus only on the advertised premium.

Compare:

  • Death benefit
  • Premium
  • Waiting periods, if applicable
  • Cash value
  • Guaranteed values
  • Policy exclusions
  • Eligibility requirements
  • Available riders
  • Financial strength of the insurer

Advantages and Disadvantages of Whole Life Insurance

Lifetime Coverage

Whole life insurance is designed to provide coverage for the insured’s lifetime, as long as the policy remains in force and its requirements are met. This can make it useful for people who want permanent protection rather than coverage that ends after a specific term.

Cash Value

Whole life insurance includes a cash value component that can grow over time according to the policy’s terms. The policy owner may be able to access this value through withdrawals or policy loans, although doing so can affect the policy and its benefits.

Guaranteed Death Benefit

A whole life policy is designed to provide a death benefit to the named beneficiaries when the insured dies, provided the policy remains in force, and applicable policy conditions are satisfied. The guaranteed amount is stated in the policy contract.

Potential Access to Cash Value

Depending on the policy, the owner may be able to borrow against or withdraw part of the accumulated cash value. However, outstanding loans, withdrawals, and interest can reduce the policy’s cash value or death benefit.
Disadvantages of Whole Life Insurance

Higher Premiums

Whole life insurance generally costs more than term life insurance with a comparable death benefit. The higher premium reflects the permanent coverage and cash value features included in the policy.

Early Cash Value May Be Limited

Cash value may be relatively limited during the early years of some whole life policies. The NAIC recommends reviewing the policy illustration to understand how guaranteed and non-guaranteed values may develop over time.

Policy Loans Can Affect Coverage

Borrowing against cash value can provide access to funds, but unpaid policy loans and interest can reduce the death benefit and affect the policy’s value. Before taking a loan, review how it could affect the policy’s long-term performance.

LOCK IN YOUR LIFETIME RATE

Secure permanent protection and guaranteed cash value growth for your family’s future. Let Assurance Gurus make finding the right whole life policy clear, transparent, and hassle-free.

Final Thoughts on Whole Life Insurance Quotes

Getting whole life insurance quotes is only the first step in choosing permanent life insurance. The right comparison goes beyond the monthly premium. Look at the death benefit, guaranteed cash value, premium structure, policy fees, riders, non-guaranteed values, loan provisions, and insurer strength. Also compare whole life with term insurance if your primary objective is affordable protection for a specific period.

The NAIC recommends understanding the policy’s guarantees, non-guaranteed values, premiums, cash value, and future benefits before purchasing life insurance. A careful comparison can help you identify a policy that fits your coverage needs and long-term financial goals rather than choosing based on an attractive initial quote alone.

If you are researching whole life insurance quotes online, use the quote as the beginning of your evaluation, not the end. Review the actual policy contract and illustration before making a final decision.

Frequently Asked Questions About Whole Life Insurance Quotes

A whole life insurance quote is an estimate of the premium you may pay for a whole life policy based on factors such as age, health, tobacco use, coverage amount, and policy design.

Yes. Many insurers and insurance platforms provide online quoting tools. However, an online quote may be an estimate rather than a final approved premium.

Many insurers and online platforms allow consumers to request quotes without paying a fee. Always check the provider's terms and understand whether you are receiving an estimate or an insurance offer.

A whole life quote is for permanent coverage with a cash-value component, while a term life quote generally covers a specific period and does not ordinarily build cash value.

Some providers can provide preliminary quotes quickly, but an instant quote does not necessarily mean the policy has been fully underwritten or approved.