Final Expense Life Insurance

Final Expense Life Insurance: 2026 Costs & Coverage Guide

Final expense life insurance is a small, permanent whole life policy built to cover funeral costs, burial or cremation expenses, and other bills that arrive in the days immediately following a death. Coverage amounts typically run from $5,000 to $25,000, and some insurers offer face amounts up to $50,000. Most applicants qualify through simplified issue underwriting, a short health questionnaire, or through guaranteed issue underwriting, which requires no health questions at all. That combination makes final expense insurance one of the more accessible types of life insurance for older adults and for anyone with a health condition that would complicate approval for a larger policy.

This guide explains what final expense insurance covers, how much it typically costs, how it compares to term and traditional whole life insurance, the four underwriting structures carriers use, and how to calculate the coverage amount that fits your situation.

Quick Answer

Final expense life insurance is a permanent whole life policy with a death benefit generally between $5,000 and $25,000, and up to $50,000 with some insurers. It pays a tax-free lump sum to your beneficiary to cover funeral, burial, or cremation costs, along with any remaining medical bills or small debts. Approval usually depends on a short health questionnaire rather than a medical exam, and level benefit policies can activate within days. Guaranteed issue policies, which ask no health questions, typically include a waiting period of about two years before the full death benefit applies to a death from natural causes.

Key Takeaways

  • Final expense insurance is a form of whole life insurance with a modest death benefit, designed to cover end-of-life costs rather than replace income.
  • Coverage typically ranges from $5,000 to $25,000; some carriers offer face amounts up to $50,000, according to U.S. News research.
  • The National Funeral Directors Association’s General Price List Study puts the median cost of a funeral with viewing and burial at $8,300, and with cremation at $6,280.
  • Social Security’s one-time lump-sum death payment has been capped at $255 since 1954, per the Social Security Administration and the Congressional Research Service, and covers only a small fraction of typical funeral costs.
  • Carriers use four main underwriting structures: level benefit, graded benefit, modified benefit, and guaranteed issue, each trading approval speed against a waiting period before the full benefit applies.
  • Before buying, check an insurer’s financial strength rating from AM Best and its complaint record through the National Association of Insurance Commissioners (NAIC) or your state insurance department.

What Is Final Expense Life Insurance?

Final expense life insurance, also called burial insurance or funeral insurance, is a type of permanent whole life insurance built around a single purpose: making sure your family isn’t left paying for your funeral, burial, or other final bills out of pocket. Like other whole life insurance, it stays in force for your entire life as long as premiums are paid, and many policies build modest cash value over time that you may be able to borrow against or withdraw.
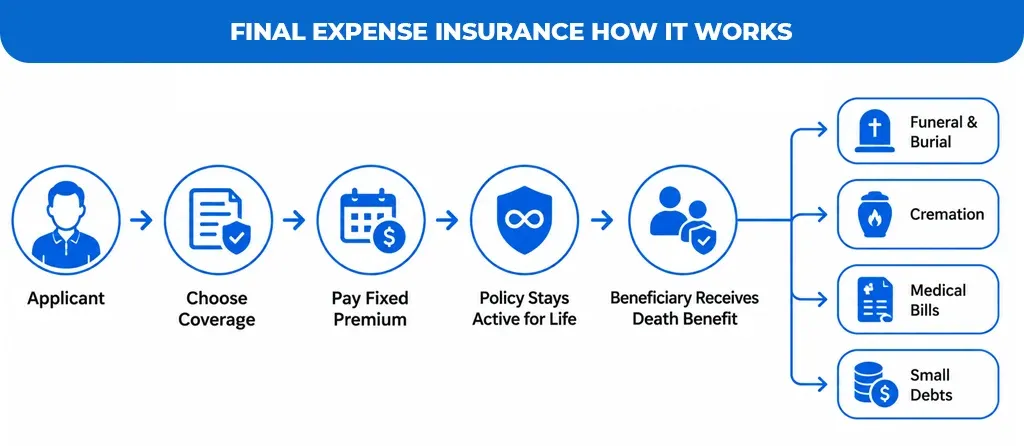
Final Expense Insurance How It Works

The distinguishing feature is underwriting. A standard term or whole life policy usually requires a medical exam for larger coverage amounts, while final expense insurance is typically underwritten through simplified issue (a short list of health questions) or guaranteed issue (no health questions at all). That trade-off is what makes the coverage accessible to seniors and people managing chronic health conditions, in exchange for a smaller death benefit and, in many cases, a higher cost per dollar of coverage than a comparable term policy.

When the insured dies, the insurer pays a tax-free death benefit directly to the named beneficiary. The payout isn’t restricted to funeral expenses; a beneficiary can use it for any purpose. In practice, most families apply it to:

  • Funeral home services, burial, or cremation costs
  • Caskets, urns, vaults, and cemetery or burial plot fees
  • Outstanding medical bills or hospice care not covered by other insurance
  • Small remaining debts, such as credit card balances or final utility bills

Why Final Expense Coverage Exists: The Cost Gap

Two figures explain why final expense insurance exists. According to the National Funeral Directors Association’s General Price List Study, the national median cost of a funeral with viewing and burial is $8,300, and a funeral with viewing and cremation runs about $6,280. Neither figure includes the cemetery plot, burial vault, or headstone, which the NFDA notes can add several thousand dollars more, and funeral costs vary by region, with the Northeast generally running above the national median.

Social Security does provide a one-time lump-sum death payment, but according to the Social Security Administration and a Congressional Research Service report, that payment has been capped at $255 since 1954 and is limited to an eligible surviving spouse or dependent child. It was never designed to cover a modern funeral, and it doesn’t come close. Final expense insurance exists to close the gap between what a funeral costs today and what a family typically has on hand in cash.

BRIDGE THE COST GAP

Funeral costs have climbed significantly while government benefits remain fixed at $255. Bridge the gap between today’s expenses and your savings with a personalized policy.

How Much Does Final Expense Insurance Cost?

Premiums depend on your age, sex, tobacco use, health class, and the coverage amount you choose, so there’s no single rate that applies to every applicant. As one example of current market pricing, Progressive advertises a RAPIDecision Final Expense policy, issued through eFinancial, starting at $62 per month for coverage between $5,000 and $40,000. Rates from other carriers will differ, and the only reliable way to know your own premium is to get a personalized quote, since insurers price risk differently depending on your health class and the underwriting type you qualify for.

Because final expense policies carry smaller death benefits and simplified underwriting, the cost per $1,000 of coverage is generally higher than a healthy applicant would pay for term life insurance. That’s the trade-off for guaranteed acceptance or a short health questionnaire, and it’s worth comparing against simplified issue term coverage if you’d qualify for one.

Final Expense vs. Term and Traditional Whole Life Insurance

Final expense insurance is a form of whole life insurance, but it’s built around a narrower use case than a standard term or whole life policy. The core distinction is purpose: final expense insurance covers a fixed, relatively predictable cost, while term and traditional whole life insurance are built to replace income or support long-term financial goals for beneficiaries.

FeatureFinal ExpenseTerm Life InsuranceTraditional Whole Life
Coverage amount$5,000–$25,000 typical (up to $50,000 with some insurers)$100,000–$1,000,000+$50,000–$1,000,000+
Medical requirementsShort health questionnaire, or no health questions (guaranteed issue)Medical exam typically required for larger amountsMedical exam typically required
Policy durationPermanent, lasts for life if premiums are paidFixed term, usually 10–30 yearsPermanent, lasts for life if premiums are paid
Primary purposeCover funeral, burial, and end-of-life costsReplace income, cover a mortgage or dependents’ needsEstate planning, income replacement, cash value growth
Underwriting speedOften days; same-day approval possibleTypically 2–6 weeks with exam and records reviewTypically 2–6 weeks with exam and records review

When to Choose Which

Final expense insurance tends to fit seniors, or anyone with a health condition that would complicate traditional underwriting or push term insurance premiums higher than the coverage amount justifies. If the goal is narrowly to keep funeral and final bills off your family, it’s usually the more efficient product, since you aren’t paying for underwriting complexity or a coverage amount you don’t need. Term life insurance remains the better fit for someone still working, with dependents, a mortgage, or income that would need to be replaced.
When to Choose Which
Final expense insurance tends to fit seniors, or anyone with a health condition that would complicate traditional underwriting or push term insurance premiums higher than the coverage amount justifies. If the goal is narrowly to keep funeral and final bills off your family, it's usually the more efficient product, since you aren't paying for underwriting complexity or a coverage amount you don't need. Term life insurance remains the better fit for someone still working, with dependents, a mortgage, or income that would need to be replaced.
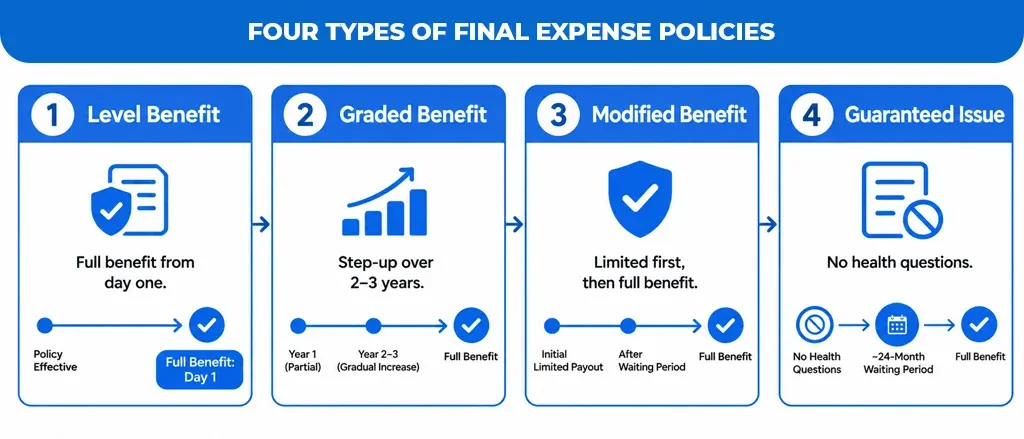
Four Types of Final Expense Policies
The Four Main Types of Final Expense Policies
Final expense carriers generally sell coverage through one of four underwriting structures. The difference between them comes down to how much health information the insurer collects and how quickly the full death benefit becomes active.
Level Benefit: Full coverage is active from day one once you're approved. This is typically reserved for applicants who pass a simplified health questionnaire.
Graded Benefit: Coverage steps up over the first two to three years. If death occurs from natural causes during that window, beneficiaries receive a reduced payout rather than the full face amount; accidental death is usually covered in full immediately.
Modified Benefit: Similar to graded benefit, but the payout during the initial waiting period is typically limited to a return of premiums paid, plus interest, rather than any portion of the face value.
Guaranteed Issue: No medical questions at all; approval is essentially automatic within the eligible age range, commonly 50 to 85. The trade-off is a waiting period, commonly around 24 months, before the full death benefit applies to a non-accidental death.
If you can answer a short health questionnaire and pass it, level benefit coverage is usually the better value, since the full death benefit is active immediately instead of after a waiting period. Guaranteed issue coverage is best reserved for applicants who would not otherwise qualify.
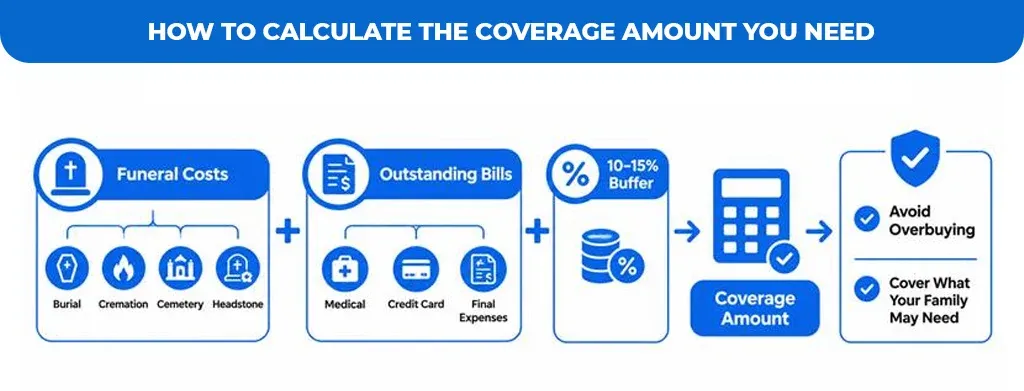
How to Calculate the Coverage Amount You Need
The right death benefit is the number that covers your local funeral costs, any debt you don't want passed on, and a reasonable buffer, no more and no less. Overbuying raises your premium without adding meaningful protection.
How to Calculate the Coverage Amount You Need
Research local funeral costs for both burial and cremation. Pricing varies by region and by funeral home. The FTC's Funeral Rule requires funeral homes to provide an itemized General Price List on request, which is the most accurate way to estimate your own local cost.
Add any outstanding medical or credit card debt you'd want the policy to help clear, since these obligations don't disappear at death and can fall to the estate.
Build in a buffer, commonly cited as 10–15% of the total, for cemetery fees, a headstone, transportation, or other add-ons that aren't included in published funeral averages.
If you'd like a more precise number based on your location, age, and existing coverage, a licensed agent can run the math against current local pricing rather than a national average.
The Four Main Types of Final Expense Policies

Final expense carriers generally sell coverage through one of four underwriting structures. The difference between them comes down to how much health information the insurer collects and how quickly the full death benefit becomes active.

  • Level Benefit: Full coverage is active from day one once you’re approved. This is typically reserved for applicants who pass a simplified health questionnaire.
  • Graded Benefit: Coverage steps up over the first two to three years. If death occurs from natural causes during that window, beneficiaries receive a reduced payout rather than the full face amount; accidental death is usually covered in full immediately.
  • Modified Benefit: Similar to graded benefit, but the payout during the initial waiting period is typically limited to a return of premiums paid, plus interest, rather than any portion of the face value.
  • Guaranteed Issue: No medical questions at all; approval is essentially automatic within the eligible age range, commonly 50 to 85. The trade-off is a waiting period, commonly around 24 months, before the full death benefit applies to a non-accidental death.

If you can answer a short health questionnaire and pass it, level benefit coverage is usually the better value, since the full death benefit is active immediately instead of after a waiting period. Guaranteed issue coverage is best reserved for applicants who would not otherwise qualify.

How to Calculate the Coverage Amount You Need

The right death benefit is the number that covers your local funeral costs, any debt you don’t want passed on, and a reasonable buffer, no more and no less. Overbuying raises your premium without adding meaningful protection.

How to Calculate the Coverage Amount You Need

  • Research local funeral costs for both burial and cremation. Pricing varies by region and by funeral home. The FTC’s Funeral Rule requires funeral homes to provide an itemized General Price List on request, which is the most accurate way to estimate your own local cost.
  • Add any outstanding medical or credit card debt you’d want the policy to help clear, since these obligations don’t disappear at death and can fall to the estate.
  • Build in a buffer, commonly cited as 10–15% of the total, for cemetery fees, a headstone, transportation, or other add-ons that aren’t included in published funeral averages.

If you’d like a more precise number based on your location, age, and existing coverage, a licensed agent can run the math against current local pricing rather than a national average.
How to Choose a Final Expense Insurance Company

Check the insurer’s financial strength rating from AM Best, which evaluates an insurance company’s ability to pay future claims.

  • Review the insurer’s complaint history through the National Association of Insurance Commissioners (NAIC) or your state insurance department.
  • Confirm which underwriting type you’re being offered: level, graded, modified, or guaranteed issue, and ask directly about any waiting period.
  • Compare the cost per $1,000 of coverage across two or three carriers rather than accepting the first quote you receive.
  • Ask whether the policy builds cash value and whether the premium is guaranteed not to increase for the life of the policy.

Conclusion

Securing final expense life insurance is the ultimate, compassionate step to ensure your family is never burdened by unexpected funeral costs, medical bills, or lingering debts. By selecting a tailored plan that aligns with your specific budget and health profile, you lock in permanent peace of mind and protect your loved ones from severe financial stress during a difficult time.

At Assurance Gurus, we make securing your end-of-life protection fast, transparent, and completely stress-free. Don’t leave your family’s financial security to chance. Take advantage of budget-friendly plans, clear pricing, and flexible coverage options designed for every age and budget.

ULTIMATE PEACE OF MIND

Protect your loved ones from severe financial stress during a difficult time. Let Assurance Gurus make securing your end-of-life protection fast, transparent, and completely stress-free.

Frequently Asked Questions (FAQs)

Most final expense policies use simplified issue underwriting instead of a physical exam. You'll answer a short set of yes-or-no health questions about conditions such as heart disease, cancer, or recent hospitalizations, and the carrier decides based on your answers and, often, a review of your prescription history. Guaranteed issue policies ask no health questions at all.

That depends on your existing savings and coverage. If you don't already have funds set aside specifically for end-of-life costs, or a paid-up whole life policy or prepaid funeral contract that covers the same expenses, a fixed monthly premium can be a reasonable way to keep that cost off your family. If you already have adequate savings or coverage, the added premium may not be necessary.

The main drawbacks are a higher cost per dollar of coverage compared with term life insurance, a death benefit too small for income replacement, and, for guaranteed issue policies specifically, a waiting period of roughly two years before the full benefit is payable for a non-accidental death. It's also possible to overpay relative to a term or traditional whole life policy if you would have qualified for standard underwriting at a similar price.

Yes, $50,000 is a real, available face amount from some final expense insurers, but it sits at the top of the typical range; most policies are written between $5,000 and $25,000. Higher amounts are more often available through simplified issue underwriting, which requires passing health questions, rather than through guaranteed issue.

The terms are generally used interchangeably in the industry. Both describe a small, permanent whole life policy intended to cover funeral, burial, or cremation costs, along with related final bills. Some carriers use one term over the other in marketing, but the underlying product structure is the same.