
In 2025, policyholders who sold their life insurance through a settlement received about nine times what their insurer would have paid on surrender, according to the Life Insurance Settlement Association. That gap is why it pays to understand the number on your statement before you cancel.
Quick answer: The cash surrender value of life insurance is the amount the insurer pays if you cancel a permanent policy: your cash value minus any surrender charges and unpaid loans. Only the portion above the premiums you’ve paid is taxable. Term life insurance has no cash surrender value.
What Is the Cash Surrender Value of Life Insurance?
The cash surrender value is the net amount an insurer pays you when you voluntarily cancel a permanent life insurance policy before it matures or pays a death benefit. It equals the policy’s accumulated cash value minus surrender charges and any outstanding loans and interest. Once you take it, the coverage ends.
Cash value vs. cash surrender value
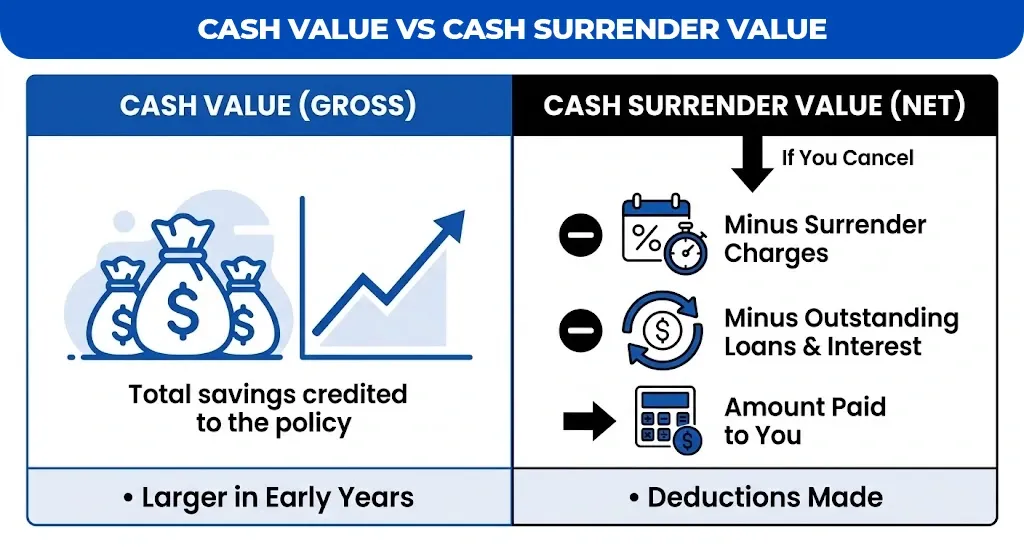
Your annual statement may show two numbers. The cash value (sometimes called the accumulated or gross value) is everything credited to the policy so far. The cash surrender value is what you’d actually receive today if you canceled.
| Feature | Cash value (gross) | Cash surrender value (net) |
| What it measures | Total savings credited to the policy | Amount paid to you if you cancel |
| Surrender charges | Not deducted | Deducted |
| Outstanding loans | Not deducted | Deducted, with accrued interest |
| When it matters | Borrowing capacity and long-term growth | The cancel-or-keep decision |
| Gap between the two | Largest in early policy years | Shrinks as surrender charges expire |
Which policies have cash surrender value?
| Policy type | Cash surrender value? | Notes |
| Whole life | Yes | Guaranteed schedule; dividends can add more on participating policies |
| Universal life | Yes | Depends on premiums paid, interest credited, and monthly charges |
| Indexed universal life | Yes | Index-linked growth with a floor, minus charges |
| Variable life and variable universal life | Yes | Invested in subaccounts; value can fall with the market |
| Final expense (small whole life) | Yes, usually small | Builds slowly because face amounts are low |
| Term life | No | Pure protection; nothing builds up to cash out |
Assurance Gurus explains how each permanent type builds value in its guides to cash value life insurance and permanent life insurance.
How to Calculate Cash Surrender Value
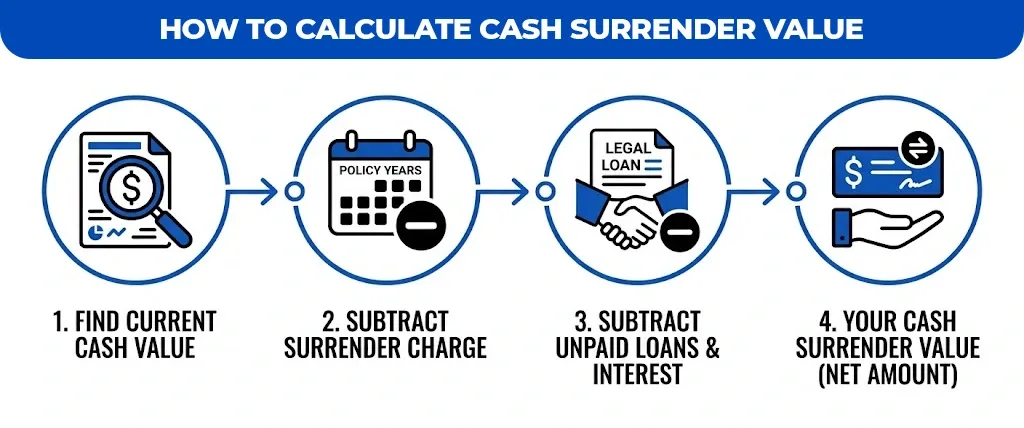
To calculate cash surrender value, start with the current cash value, subtract the surrender charge for your policy year, then subtract any unpaid loans and accrued interest. Your insurer will confirm the exact figure in writing on request.
The math, step by step
1. Find the current cash value on your latest annual statement or by requesting an in-force illustration.
2. Look up the surrender charge for the current policy year in your contract’s surrender schedule.
3. Add up outstanding loans and accrued interest.
4. Subtract steps 2 and 3 from step 1.
Example (illustrative): A universal life policy in its sixth year has $40,000 of cash value, a 5% surrender charge, and an $8,000 policy loan with $480 of unpaid interest.
| Item | Amount |
| Current cash value | $40,000 |
| Surrender charge (5%) | −$2,000 |
| Outstanding loan plus interest | −$8,480 |
| Cash surrender value | $29,520 |
Understanding surrender charge schedules
Surrender charges let the insurer recover its upfront commission and underwriting costs when a policy ends early. They are highest in the first year and shrink each year until they reach zero, typically after 10 to 15 years, per NerdWallet. The exact percentages vary by insurer and product, so the schedule below is only an example of the pattern.
| Policy year | Example surrender charge |
| 1 | 10% of cash value |
| 3 | 8% |
| 5 | 6% |
| 7 | 4% |
| 9 | 2% |
| 11 and later | 0% |
Universal life contracts usually print a surrender charge schedule in dollars or percentages. Whole life policies often build the charge into a lower guaranteed cash value in early years, so the cash value shown already reflects it. Assurance Gurus explains universal life charges in its universal life insurance guide.
Cash surrender value on term life insurance
Term life insurance has no cash surrender value. Premiums pay only for the death benefit during the term, so if you cancel, coverage simply ends and you receive nothing. The exception is return-of-premium (ROP) term, which refunds premiums if you outlive the term; some ROP contracts also pay a partial refund if you cancel after a set number of years, so check yours. A term policy with a conversion option has no cash value either, but it may be convertible to permanent coverage or sellable in a life settlement before the conversion period ends.
Cash Surrender Value Benchmarks: $10k, $100k, and $500k Policies
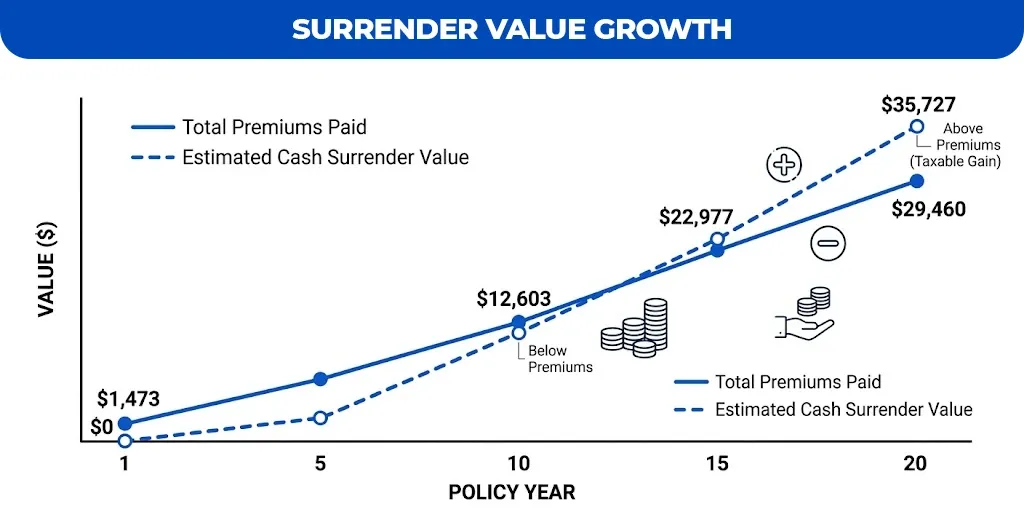
Whole life cash surrender value is usually zero in year one and stays below total premiums paid for roughly the first 10 to 15 years. In 2026 sample illustrations, a $100,000 dividend-paying policy bought at 40 is worth about $12,600 after 10 years and $35,700 after 20.
Key drivers of surrender value growth
• Policy duration: surrender charges and upfront costs weigh heavily on early years.
• Premium funding: paying more than the minimum, or adding paid-up additions, builds value faster.
• Mortality and expense charges: higher cost of insurance, especially at older ages, slows growth.
• Dividends: participating whole life policies from mutual insurers can grow noticeably faster, though dividends aren’t guaranteed.
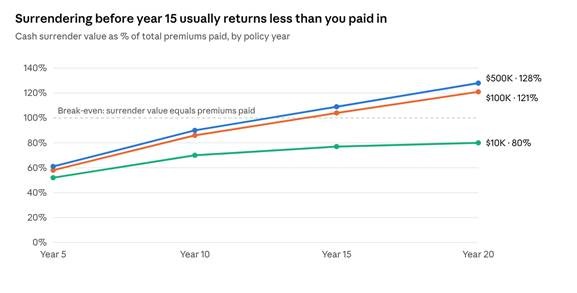
Cash surrender value as a share of premiums paid
Estimated $10,000 whole life policy (issue age 60, male)
| Policy year | Total premiums paid | Est. cash surrender value | Surrender value vs. premiums |
| 1 | $317 | $0 | 0% |
| 5 | $1,584 | $825 | 52% |
| 10 | $3,168 | $2,202 | 70% |
| 15 | $4,752 | $3,645 | 77% |
| 20 | $6,336 | $5,069 | 80% |
These are estimates scaled to one-tenth of Choice Mutual’s $100,000 non-dividend whole life illustration for a 60-year-old man. Real $10,000 final expense policies usually carry higher premiums per $1,000 because of per-policy fees, so their surrender values can be lower relative to what you pay in.
$100,000 dividend-paying whole life policy (issue age 40, male)
| Policy year | Total premiums paid | Cash surrender value | Surrender value vs. premiums |
| 1 | $1,473 | $0 | 0% |
| 5 | $7,365 | $4,261 | 58% |
| 10 | $14,730 | $12,603 | 86% |
| 15 | $22,095 | $22,977 | 104% |
| 20 | $29,460 | $35,727 | 121% |
$500,000 dividend-paying whole life policy (issue age 40, male)
| Policy year | Total premiums paid | Cash surrender value | Surrender value vs. premiums |
| 1 | $7,000 | $0 | 0% |
| 5 | $35,000 | $21,305 | 61% |
| 10 | $70,000 | $63,015 | 90% |
| 15 | $105,000 | $114,884 | 109% |
| 20 | $140,000 | $178,633 | 128% |
Source: Choice Mutual whole life illustrations for a non-tobacco preferred rating, valid as of March 9, 2026. Tables 2 and 3 include non-guaranteed dividends; premium totals and percentages are our arithmetic.
Note: Illustrated values aren’t guarantees. Ask your insurer for an in-force illustration showing both the guaranteed and current surrender values before you decide anything.
Tax Implications: Is Cash Surrender Value Taxable?
Cash surrender value is taxable only to the extent it exceeds your cost basis, which is generally the total premiums you’ve paid. The portion up to your premiums comes back tax-free; anything above that is taxed as ordinary income, not capital gains. IRS Publication 525 explains that when you surrender a policy for cash, you include in income the proceeds that exceed the cost of the policy.
The cost basis rule
Your cost basis is the premiums you’ve paid, minus any premiums refunded, dividends taken in cash, and earlier tax-free withdrawals. For a policy that isn’t a modified endowment contract (MEC), partial withdrawals are taxed first-in, first-out (FIFO): your basis comes out first, tax-free, and only later dollars are taxable.
Example: The $100,000 policy in Table 2 is surrendered in year 20 for $35,727 after $29,460 of premiums, with dividends used to buy paid-up additions. The taxable gain is $6,267, reported as ordinary income on the Form 1099-R the insurer sends.
How gains above basis are taxed
IRC §7702 is the section that defines what counts as life insurance for tax purposes; a policy that qualifies gets tax-deferred cash value growth and an income-tax-free death benefit. The tax on a surrender itself comes from the annuity and insurance distribution rules in IRC §72(e), which tax the excess over basis as ordinary income. If the policy failed the federal 7-pay test and became a MEC, withdrawals and loans are taxed gain-first, and taxable amounts taken before age 59½ generally carry an extra 10% penalty.
The hidden tax trap: surrendering with a loan
When you surrender a policy with an outstanding loan, the insurer uses the cash value to repay the loan. The IRS treats that repayment as money you received, so you can owe tax on a gain even if the check is small.
| Item | Amount |
| Gross cash value | $50,000 |
| Outstanding loan and interest | $45,000 |
| Cash you actually receive | $5,000 |
| Total premiums paid (basis) | $30,000 |
| Taxable gain | $20,000 ($50,000 − $30,000) |
The same thing happens if a heavily borrowed policy lapses. Before surrendering any policy with a loan, ask the insurer for a projected 1099-R amount and talk to a tax professional. Assurance Gurus covers related rules in do you pay taxes on life insurance and is life insurance taxable.
4 Alternatives to Surrendering Your Life Insurance Policy
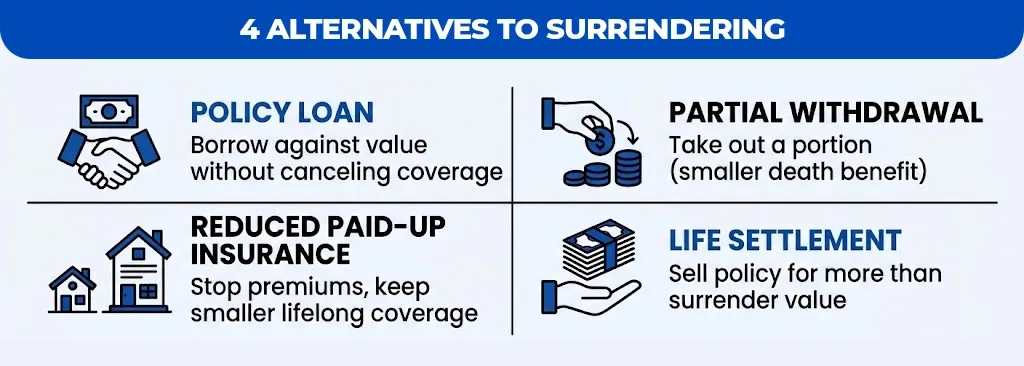
Before you surrender, compare four alternatives: a policy loan, a partial withdrawal, reduced paid-up insurance, and a life or viatical settlement. Each keeps more value or more coverage than a full surrender in the right situation.
Alternative 1: Tax-free policy loans
You can borrow against your cash value without canceling coverage or passing a credit check. On a non-MEC policy, the loan isn’t taxable while the policy stays in force. Interest accrues at a rate set in your contract, and any unpaid balance is subtracted from the death benefit. Best for short-term cash needs when you still want the coverage.
Alternative 2: Partial cash withdrawals
Universal life policies, and whole life policies with paid-up additions or dividends, let you withdraw part of the cash value. Under FIFO rules, withdrawals up to your cost basis are tax-free on a non-MEC policy. The trade-off is a permanently smaller death benefit and, in some universal life policies, a partial surrender charge.
Alternative 3: Reduced paid-up insurance
Most whole life policies include a reduced paid-up nonforfeiture option. The insurer uses your cash value to buy a smaller, fully paid policy, so you stop paying premiums but keep lifelong coverage that continues to build cash value. This works well if you can’t afford premiums but still want something to leave behind for final expenses.
Alternative 4: Life settlements and viatical settlements
A life settlement sells your policy to a third-party investor for more than the cash surrender value but less than the death benefit. The buyer takes over the premiums and collects the death benefit later. Life settlement buyers generally look for insureds who are older, often 65 or more, or in declining health, with larger policies.
• In 2025, members of the Life Insurance Settlement Association paid consumers $626.6 million across 2,955 settlements, with an average payout of $212,066, compared with an average cash surrender value of $24,360 on those same policies, as reported by ThinkAdvisor and Beinsure.
• An actuarial study by Deloitte and the University of Connecticut found settlement values averaged about 20% of face amount, with a range of 17% to 33%, according to ThinkAdvisor. Offers vary widely by age, health, and premium cost.
A viatical settlement is a sale by someone who is terminally or chronically ill. Proceeds that meet IRS requirements can be excluded from income, as explained in IRS Publication 525. Many policies also include accelerated death benefit riders that pay part of the benefit early; see Assurance Gurus’ guide to life insurance with living benefits.
Note: Life settlement proceeds above your cost basis are generally taxable, and brokers’ fees reduce your net. Get at least two offers and have a tax professional review the transaction before signing.
Bonus: a 1035 exchange
If your goal is a better policy rather than cash, a Section 1035 exchange lets you move the cash value directly into a new life insurance policy or annuity without triggering tax on the gain, as allowed under IRC §1035. The new policy may have new surrender charges, so compare costs carefully.
Pros and Cons: Is Cashing Out Your Policy Worth It?
Surrendering makes sense when you no longer need the coverage, can’t keep paying, and have checked that no alternative pays more. It’s usually a poor choice in the first 10 to 15 years, when surrender charges are highest and the payout is often below what you’ve paid in.
Benefits of surrendering
• Immediate cash with no loan to repay and no interest accruing.
• No more premiums, which frees up monthly cash flow.
• Simplicity: the policy is closed and nothing needs monitoring.
• Tax-free up to basis: only the gain above premiums paid is taxed.
Drawbacks of surrendering
• Coverage ends, and replacing it later costs more because you’re older and may be less healthy.
• Surrender charges can take a large bite in early years.
• Taxable gain on older policies, plus the loan trap if you’ve borrowed heavily.
• Money left on the table: a life settlement or reduced paid-up policy may be worth more.
Decision matrix: surrender vs. loan vs. settlement vs. paid-up
| Factor | Full surrender | Policy loan | Life settlement | Reduced paid-up |
| Cash now | Net surrender value | Up to the available loan value | Usually more than surrender value | None |
| Coverage afterward | Ends | Continues, reduced by the loan | Ends for you (buyer owns it) | Continues at a lower amount |
| Future premiums | None | Still due | None (buyer pays) | None |
| Tax | Gain above basis taxed | None while in force (non-MEC) | Gain generally taxable | None at conversion |
| Best for | Coverage no longer needed | Temporary cash needs | Older insureds with large policies | Can’t pay premiums, still want coverage |
| Biggest risk | Losing coverage you’ll later need | Loan growth causing lapse | Fees and lost death benefit | Smaller death benefit |
Conclusion: Review Before You Surrender
The cash surrender value of life insurance is what’s left after surrender charges and loans, and it’s often far less than the policy is worth in other forms. Before you cancel, get an in-force illustration, calculate your taxable gain, and price at least one alternative.
| Your situation | Best next step |
| Need cash briefly, still want coverage | Policy loan |
| Want to stop premiums but keep some coverage | Reduced paid-up insurance |
| Age 65+ with a large policy you no longer need | Get life settlement offers |
| Terminally or chronically ill | Accelerated death benefit rider or viatical settlement |
| Want a better or cheaper policy | 1035 exchange to a new policy |
| No longer need coverage and surrender charges have expired | Full surrender may make sense |
Talk to Assurance Gurus Before You Cancel
Assurance Gurus helps families compare life insurance options with expert guidance from its team, from term and universal life to final expense and burial coverage. If you’re thinking about surrendering a policy, it’s worth a conversation about what coverage you still need and what it would cost to replace.
• Review whether your current policy still fits your goals and budget.
• Compare term, universal life, and final expense options if you need new coverage.
• Get clear, honest pricing with no pressure.