
Term life insurance quotes tell you how much a policy will cost before you commit to buying one, and the number can vary by hundreds of dollars a year depending on which insurer you ask. A term life insurance quote is not a bill. It is an estimate generated from a handful of details: your age, gender, health history, tobacco use, the coverage amount (death benefit) you want, and the term length you choose, usually 10, 20, or 30 years.
This guide walks through what actual 2026 term life insurance quotes look like by coverage amount and age, what pushes a quote higher or lower, how no-medical-exam quotes work, what seniors can expect to pay, and how to compare quotes from different carriers without getting a number that changes once you formally apply. Every figure below is sourced from a named insurer, comparison site, or regulatory body so you can verify it independently.
| Quick AnswerA term life insurance quote is a personalized premium estimate based on your age, gender, health, tobacco use, coverage amount, and term length. For a healthy 40-year-old on a 20-year, $500,000 policy, the current national average is $47 per month for women and $59 per month for men, according to MoneyGeek’s 2026 analysis of thousands of quotes across 30 major insurers. Getting quotes from at least three insurers is the most reliable way to find the lowest rate for your health profile. |
| Key Takeaways A 40-year-old, healthy nonsmoker pays an average of $47 (women) to $59 (men) per month for a 20-year, $500,000 term policy (MoneyGeek, 2026).Coverage amount changes the math fast: the same 40-year-old pays roughly $16–$19/month for $100,000 and $86–$109/month for $1,000,000 in 20-year term coverage (MoneyGeek, 2026).Rates are locked in for the length of your term. Waiting to buy is one of the few cost factors fully within your control.No-medical-exam term life insurance is available through accelerated and simplified-issue underwriting, typically at rates that run 10% to 25% higher than fully underwritten policies for the same coverage (Ethos, SimplyInsurance, 2026).Comparing quotes from multiple insurers with strong financial-strength ratings from AM Best is a key consumer safeguard recommended by independent financial experts. |
What Are Term Life Insurance Quotes?
A term life insurance quote is an estimated monthly or annual premium for coverage that lasts a fixed period, known as the term.
Term life insurance is temporary, pure-protection coverage. If the policyholder dies during the term, the insurer pays a tax-free lump sum, called the death benefit, to the named beneficiaries. If the term ends and the policyholder is still alive, the coverage simply expires unless it is renewed or converted. This is different from permanent products like whole life or universal life insurance, which last for life and build cash value, but which also cost significantly more for the same death benefit.
A quote is generated before formal underwriting takes place, so it is an estimate based on self-reported information. The final premium is confirmed only after the insurer completes underwriting, which may include a review of prescription history, medical records, driving records, or a medical exam, depending on the policy type.
Key Entities Behind Every Quote
- Premium: the amount you pay, usually monthly or annually, to keep the policy in force.
- Death benefit: the lump-sum payout your beneficiaries receive.
- Underwriting: the insurer’s process for assessing risk and setting your final rate.
- Level term: a policy structure where the premium and death benefit stay fixed for the entire term, the most common structure quoted online.
- Riders: optional add-ons, such as a waiver of premium or accelerated death benefit, that adjust coverage for an extra cost.
- AM Best / NAIC: AM Best rates insurers’ financial strength; the National Association of Insurance Commissioners (NAIC) coordinates state insurance regulation and consumer protection standards nationally.
How Much Do Term Life Insurance Quotes Cost in 2026?
For a healthy 40-year-old nonsmoker buying a 20-year, $500,000 term policy, the national average is $47 per month for women and $59 per month for men, based on MoneyGeek’s analysis of thousands of quotes from 30 major insurers in 2026. Most applicants across all profiles pay between $30 and $100 per month, though your personal quote depends on age, health, tobacco use, and coverage amount.
Term Life Insurance Quotes by Coverage Amount
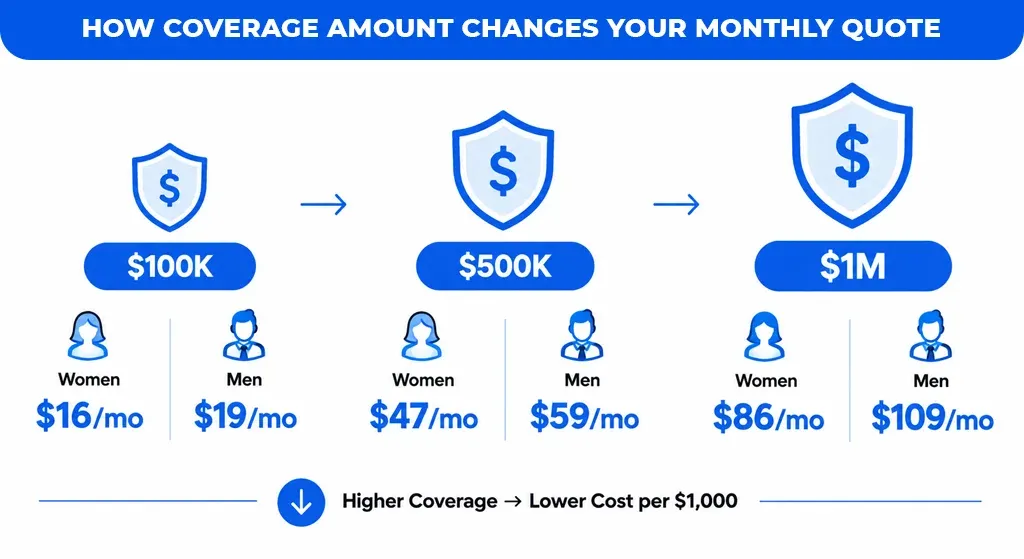
Coverage amount is one of the biggest levers on your quote. The table below compares average monthly premiums for a healthy 40-year-old nonsmoker on a 20-year term across three common coverage levels.
| Coverage Amount | Average Monthly Quote Women | Average Monthly Quote Men | Source |
| $100,000 | $16 | $19 | MoneyGeek (2026) |
| $500,000 | $47 | $59 | MoneyGeek (2026) |
| $1,000,000 | $86 | $109 | MoneyGeek (2026) |
The cost per $1,000 of coverage actually falls as the death benefit rises. MoneyGeek’s data shows a $100,000 policy for a 40-year-old nonsmoking man costs $0.19 per $1,000 of coverage, while a $1,000,000 policy for the same applicant costs about $0.11 per $1,000. This is why buying more coverage than the bare minimum is often more cost-efficient per dollar of protection, even though the total premium is higher.
How Smoking Changes Your Quote
Tobacco use is one of the single largest cost drivers in any term life insurance quote. For a $1,000,000, 20-year policy, a 40-year-old female smoker pays an average of $281 per month versus $86 for a nonsmoker, a difference of 227%. A 40-year-old male smoker pays $376 versus $109 for a nonsmoker, a 245% increase.
Most insurers move former smokers back to nonsmoker rates after 12 to 24 months of documented abstinence, though some require three to five years, so it is worth disclosing an accurate quit date when requesting quotes rather than waiting.
What Affects a Term Life Insurance Quote
Insurers price a term life insurance quote using a combination of demographic, health, and policy-design factors. The main variables are:
- Age: premiums rise the longer you wait to apply, and the rate you lock in stays fixed for the entire term.
- Gender: women generally receive lower quotes than men of the same age and health profile, reflecting differences in average life expectancy.
- Tobacco and nicotine use: smokers typically pay two to four times more than nonsmokers for the same coverage.
- Health class: insurers assign risk tiers (such as preferred, standard, or substandard) based on health history, family history, weight, blood pressure, and similar factors.
- Coverage amount (death benefit): a higher payout raises the premium but lowers the cost per $1,000 of coverage.
- Term length: a 30-year term typically costs more than a 10-year term for the same applicant and coverage amount, since the insurer’s risk window is longer.
Race, ethnicity, sexual orientation, and marital status are not permitted rating factors for individual life insurance in the United States.
How to Get Term Life Insurance Quotes Online
Getting an online term life insurance quote generally takes only a few minutes because it relies on self-reported information rather than a full underwriting file. The typical process looks like this:
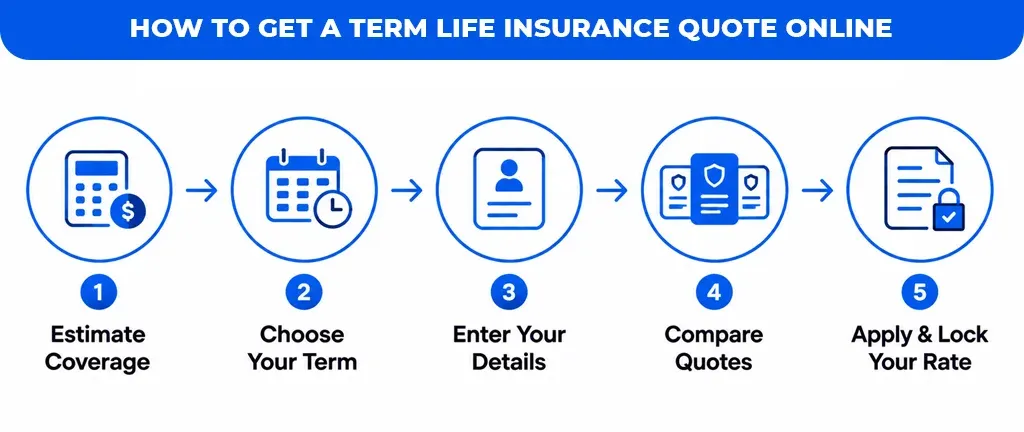
- Estimate your coverage need. A common starting formula is 10 to 15 times your annual income, plus your mortgage balance and roughly $100,000 to $150,000 per dependent child.
- Choose a term length. Match the term to a specific obligation, such as the years remaining on a mortgage or until children finish college.
- Enter basic details. Age, gender, state, tobacco use, and general health information generate an instant estimate.
- Compare quotes from at least three insurers. Rates for an identical applicant can vary significantly between carriers; MoneyGeek’s analysis found the cheapest carrier can charge less than half of the most expensive carrier for identical coverage.
- Check the insurer’s financial strength. Confirm an AM Best rating before applying, since a term policy may need to pay a claim decades after purchase.
- Complete the formal application. The instant quote becomes a locked-in rate once underwriting confirms your stated information.
Term Life Insurance Quotes With No Medical Exam
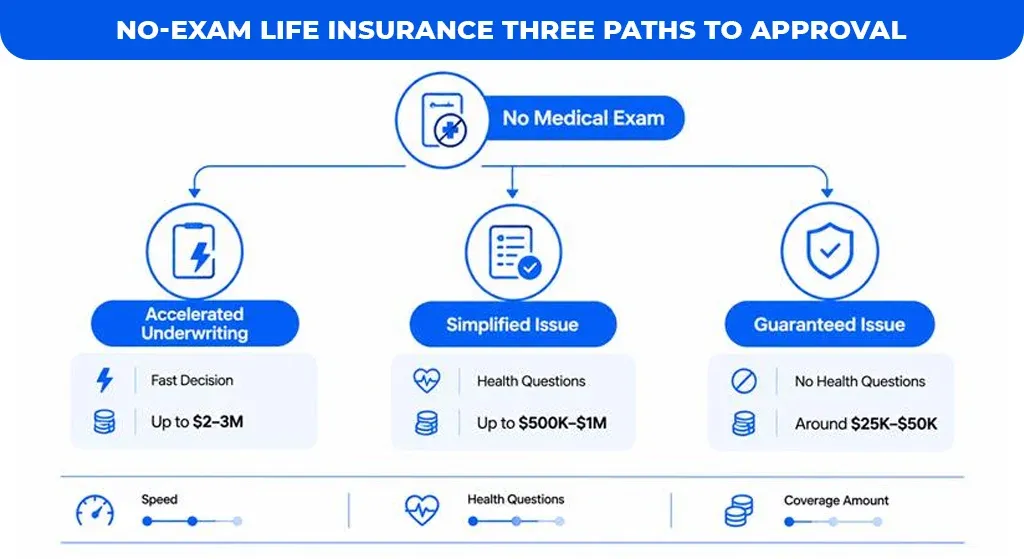
Term life insurance quotes with no medical exam replace the physical exam with health questions and electronic data checks, such as prescription history and driving records, instead of blood work. This process is generally called accelerated underwriting or simplified issue, and it is overseen at the state level with input from the NAIC’s Big Data and Artificial Intelligence Working Group and Market Conduct Examination Guidelines Working Group.
Types of No-Exam Term Life Insurance
| Underwriting Type | How It Works | Typical Coverage Limit |
| Accelerated underwriting | Uses health questions plus data sources (prescription history, driving records) for a fast decision; no physical exam for qualifying applicants | Up to $2–3 million for healthy applicants |
| Simplified issue | Shorter health questionnaire; no exam and no data pull in some cases; more expensive per dollar of coverage | Typically up to $500,000–$1 million |
| Guaranteed issue | No health questions or exam; approval is guaranteed within age limits; usually includes a graded death benefit period | Typically capped around $25,000–$50,000 |
No-exam term life insurance quotes typically run 10% to 25% higher than fully underwritten rates for the same applicant, though the gap narrows for healthy applicants who qualify for accelerated underwriting. Skipping the exam trades a modestly higher premium for speed and convenience, since some accelerated-underwriting decisions come back in minutes rather than the several weeks a traditional exam-based application can take.
Term Life Insurance Quotes for Seniors
Term life insurance quotes for seniors are still available past age 60, though the maximum issue age, coverage limits, and pricing structure vary considerably by carrier.
| Insurer | Max Issue Age (Term) | Notable Feature |
| Guardian Life | 75 | Strong financial strength; term convertible to permanent coverage |
| USAA | 70 | Convertible term options; military-affiliated membership required |
| Northwestern Mutual | 70 | High customer-experience ratings |
| MassMutual | 75 | Accommodates older seniors relative to peers |
| AARP / New York Life | Coverage to age 80 | No medical exam; open to AARP members 50+ and spouses |
AARP Term Life Insurance Quotes
The AARP Life Insurance Program, underwritten by New York Life, offers term coverage from $10,000 to $150,000 for AARP members aged 50 and older and their eligible spouses, with no medical exam required, only health questions.
- Coverage can last to age 80, and policies can be converted to permanent coverage before then without a new medical exam.
- Premiums start lower but increase at each five-year age band rather than staying level for a fixed term.
- AARP membership is required to apply, and the program carries an Exceptional financial strength rating and fewer than expected NAIC complaints, according to NerdWallet’s 2026 review.
How to Compare Term Life Insurance Quotes
Comparing term life insurance quotes accurately means holding every variable constant except the carrier. A quote is only useful for comparison if the coverage amount, term length, health class, and rider selections match across insurers.
- Match coverage amount and term length exactly. A $500,000, 20-year quote from one insurer should be compared against the same figures from another, not a different combination.
- Confirm it is a level term. A level term policy keeps the premium fixed for the full term; some low-starting-cost products increase after an initial period, which changes the real cost over time.
- Check the AM Best rating. Financial strength matters more on a decades-long term policy than on most other purchases, since the insurer must remain solvent to pay a future claim.
- Ask whether the exam is optional. Completing a medical exam when you are healthy can lower your rate compared with simplified-issue pricing for the same applicant.
- Review available riders. Waiver-of-premium, accelerated death benefit, and conversion riders can add meaningful value for a modest cost increase.
Financial commentator Clark Howard recommends a two-step filter: confirm the insurer carries an A++ (or at minimum A+) AM Best rating, then choose the cheapest quote among insurers that clear that bar, rather than optimizing for price alone.
Term Life Insurance Companies With Competitive Quotes in 2026
The insurers below are consistently named among the most competitively priced term life insurance providers in independent 2026 comparisons.
| Company | Average Monthly Rate (40, 20-yr, $500k)* | Best Known For |
| Banner Life | $37 (women) / $46 (men) | Most affordable average rate; long-term lengths up to 40 years |
| Transamerica | $37 (women) / $46 (men) | Broad age eligibility (18–80) |
| Pacific Life | $38 (women) / $54 (men) | Wide range of coverage options |
| Nationwide | $45 (women) / $56 (men) | Best no-exam term option |
| Guardian Life | Varies by profile | Financial strength and low complaint rate |
Rate rankings shift by age, health class, and state, so the cheapest company for a 30-year-old nonsmoker is not necessarily the cheapest for a 55-year-old with a health condition. Running quotes for your specific profile remains the only reliable way to identify the lowest available rate.
Term Life Insurance Quotes vs. Whole Life Insurance Quotes
Term life insurance is temporary and built purely for a death benefit, which is why its quotes are dramatically lower than permanent coverage. Whole life insurance for a 40-year-old on $500,000 in coverage averages roughly $540 to $574 per month, compared with $47 to $59 for term coverage at the same age and amount, because whole life lasts for life and builds cash values.
Universal life insurance sits between the two, offering lifelong coverage with flexible premiums, and averages roughly $336 per month at age 40 for comparable coverage. Term is generally the more cost-efficient choice for time-bound needs such as income replacement during working years or covering a mortgage, while permanent policies suit longer-term estate planning or cash-value goals.
The Bottom Line on Term Life Insurance Quotes
A term life insurance quote is only a starting estimate, but the underlying math is consistent: age, health, tobacco use, coverage amount, and term length drive the price, and rates lock in for the life of the term once you apply. Comparing quotes from at least three financially strong insurers before applying remains the most reliable way to secure the lowest premium for your health profile and coverage needs.
Ready to see your own numbers? Request term life insurance quotes from a few highly rated carriers side by side, keep the coverage amount and term length identical across each one, and confirm the AM Best rating before you apply, so the only variable left to compare is price.